College resources
Plain-English explanations, worked math, and what it means for you.
You can start with the basics.
Learn the words, follow the numbers, and understand what a choice could mean for your life. Start with the first action. Open examples and explanations when you need them, then continue in the related tool.
Your first useful action
Use your school’s official calendar to collect one deadline and its required action. Separate application, registration, payment, housing, and financial-aid dates.
A worked example
A planning row can say: registration opens August 5; adviser approval needed; contact adviser by July 29; save confirmation after registering. These dates are fictional.
What people often mix up
Admission is not course registration, and an aid estimate is not money already received. Each office may need different documents.
What to ask when you are stuck
“What must I complete before this deadline, how do I submit it, and how can I check it was received?”
Ask the organization or person responsible for the decision. Write down the answer, date, and any next action. If their answer uses an unfamiliar word, find it in Words explained below.
How to know this first action is finished
You know the responsible office, submission method, required information, and confirmation process.
Turn one school deadline into an action
- Open the official calendar or office instructions for your own school year.
- Write the action, deadline, required information, responsible office and submission method.
- Ask how to verify receipt. Plan a preparation date before the actual deadline.
Check your result: You know what to submit and how to check that the office received it.
If something changes
A calendar reminder is not a completed application. If the deadline changes, verify it with the responsible office.
Practical how-to guides
Start with one useful skill. Clear instructions and a checklist help you through it.
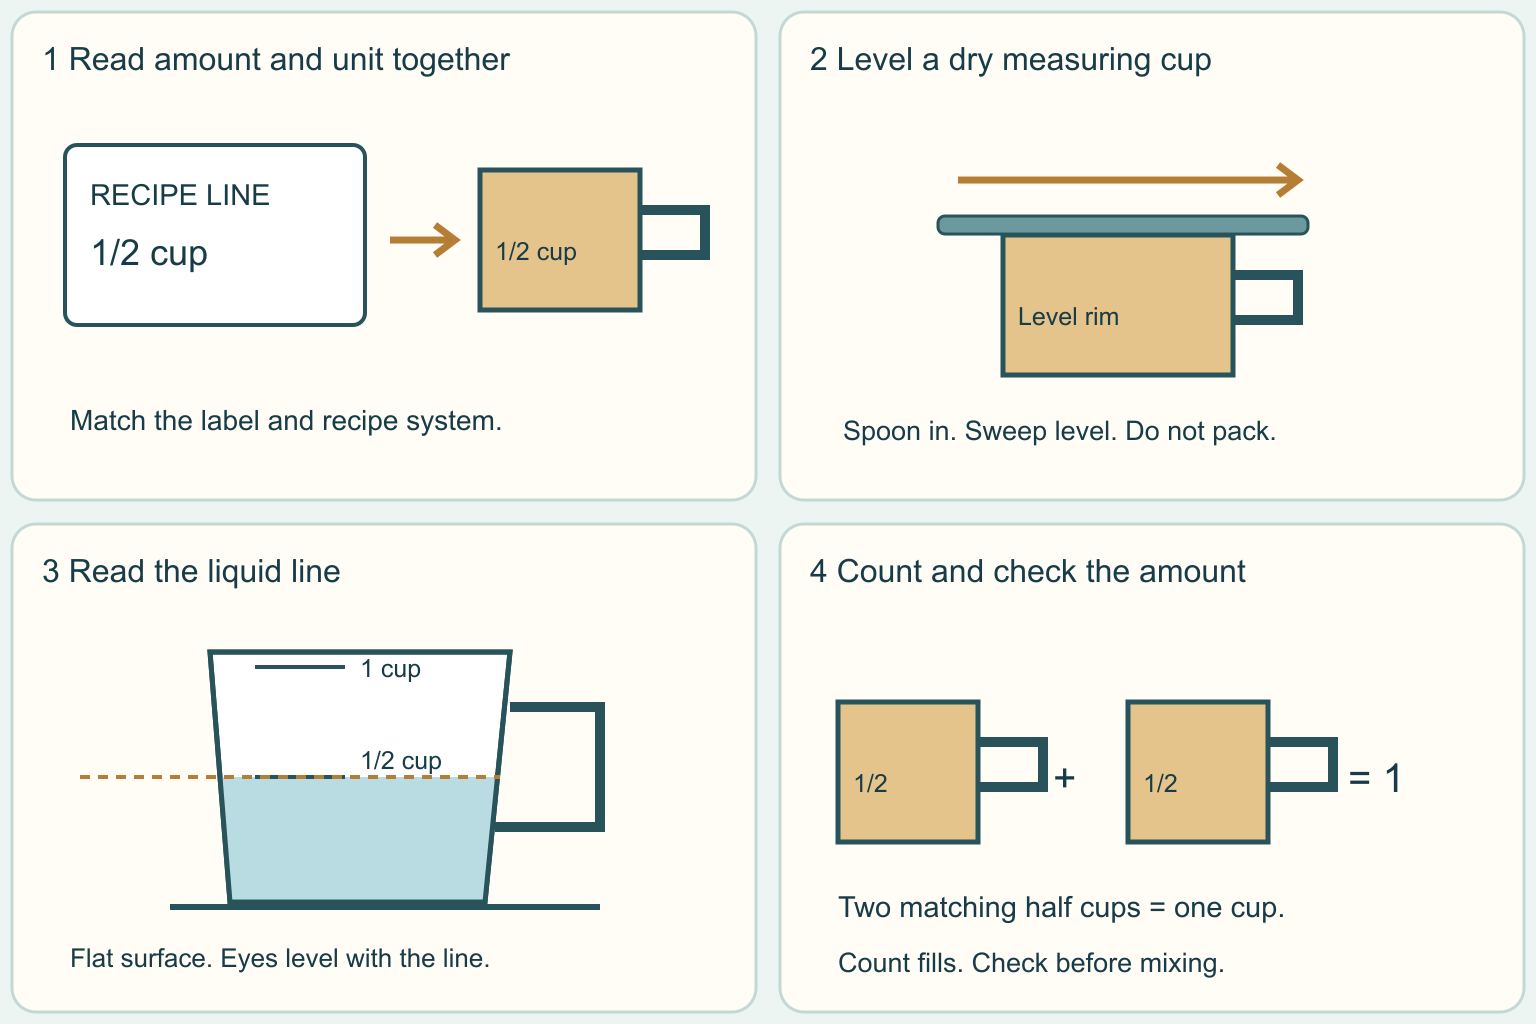
Read recipe amounts and measure dry and liquid ingredients
Learn which measuring tool to pick, what the little labels mean, and how to check an amount before mixing. Start with room-temperature water for liquid practice.
4 clear steps · checklist & download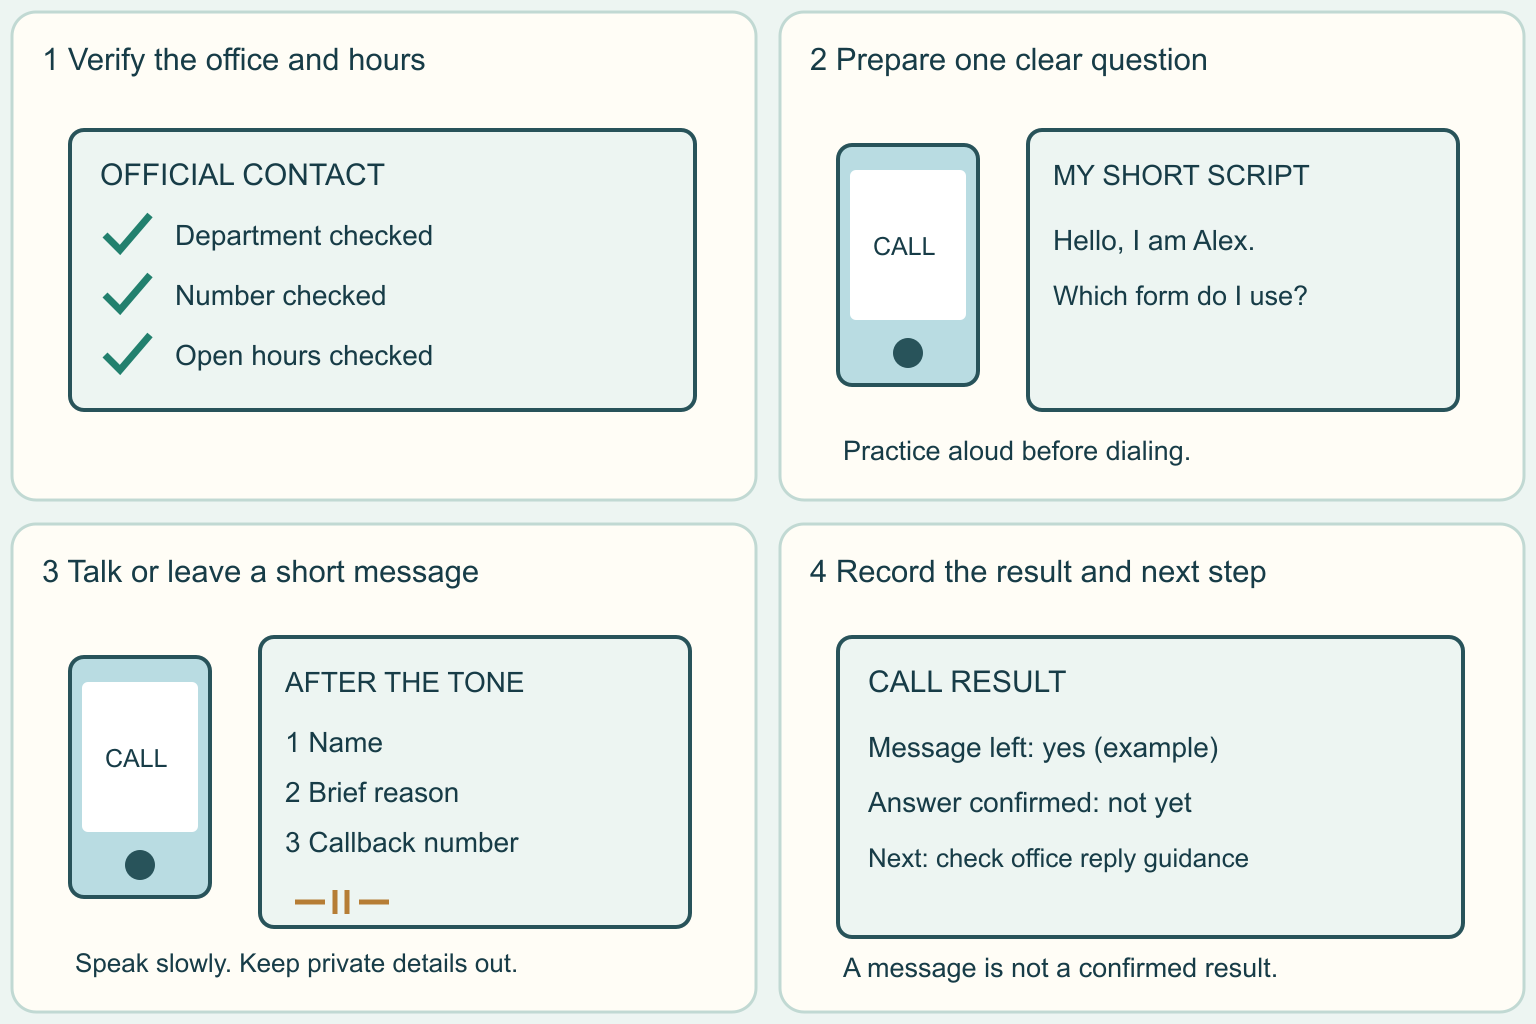
Make a routine office call and leave a clear voicemail
Prepare one simple question, call a verified office number, and know what to say if a person or voicemail answers.
4 clear steps · checklist & download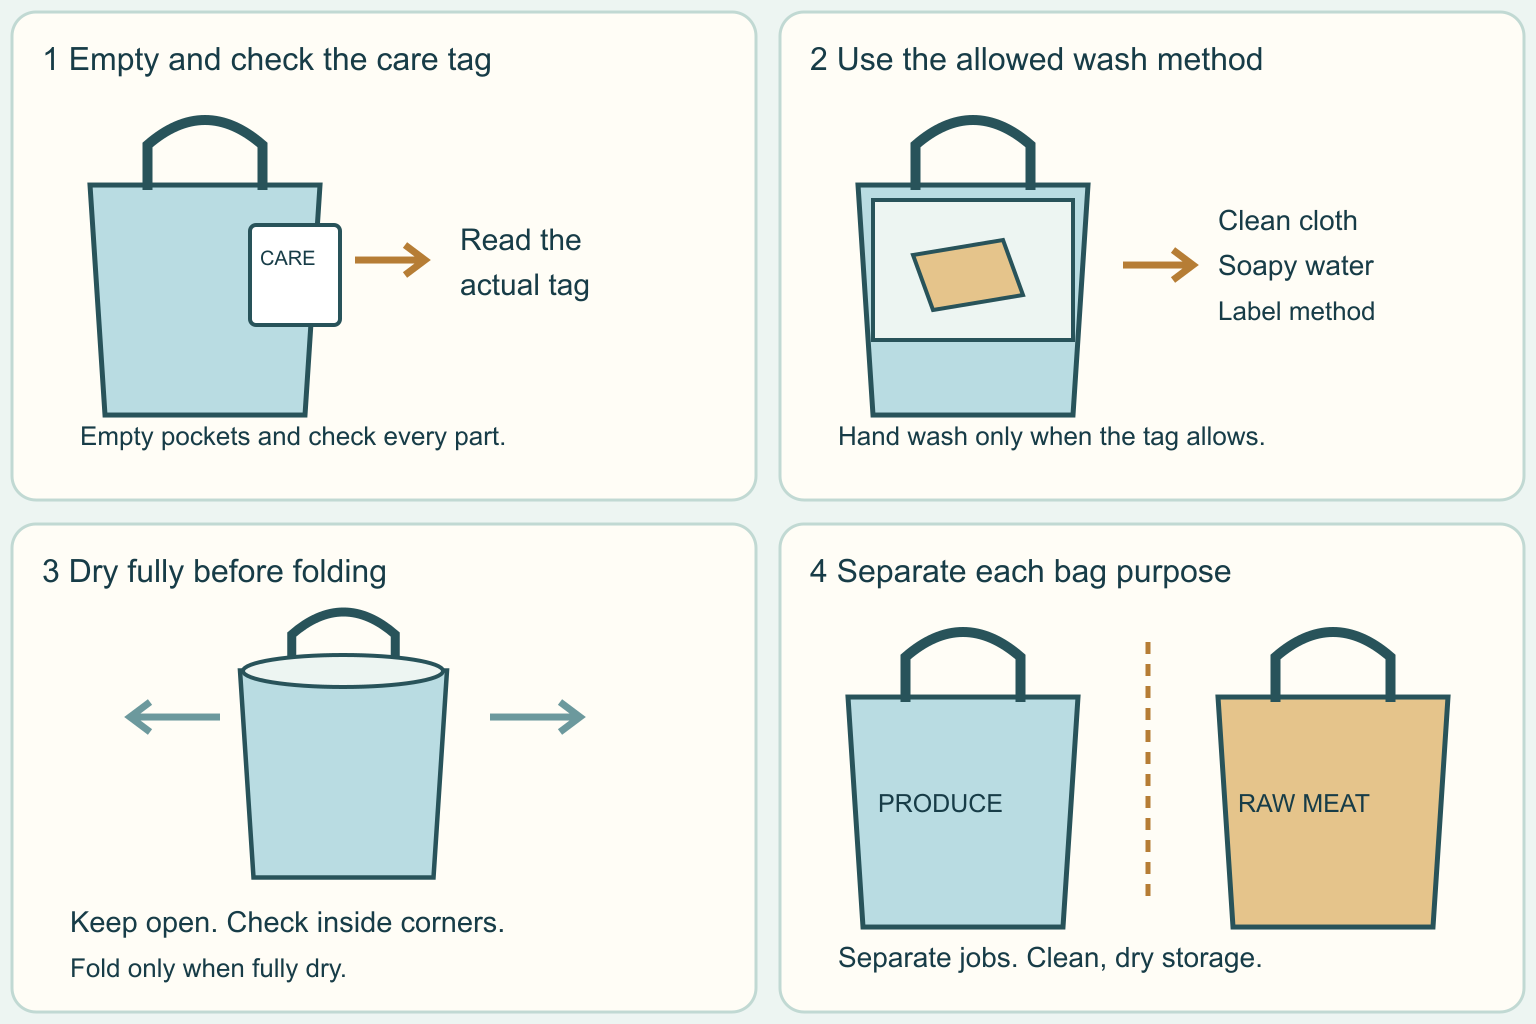
Clean, dry and sort your reusable grocery bags
Start with one ordinary reusable shopping bag. Read its care label, clean it the allowed way, and keep food bags separate from other uses.
4 clear steps · checklist & download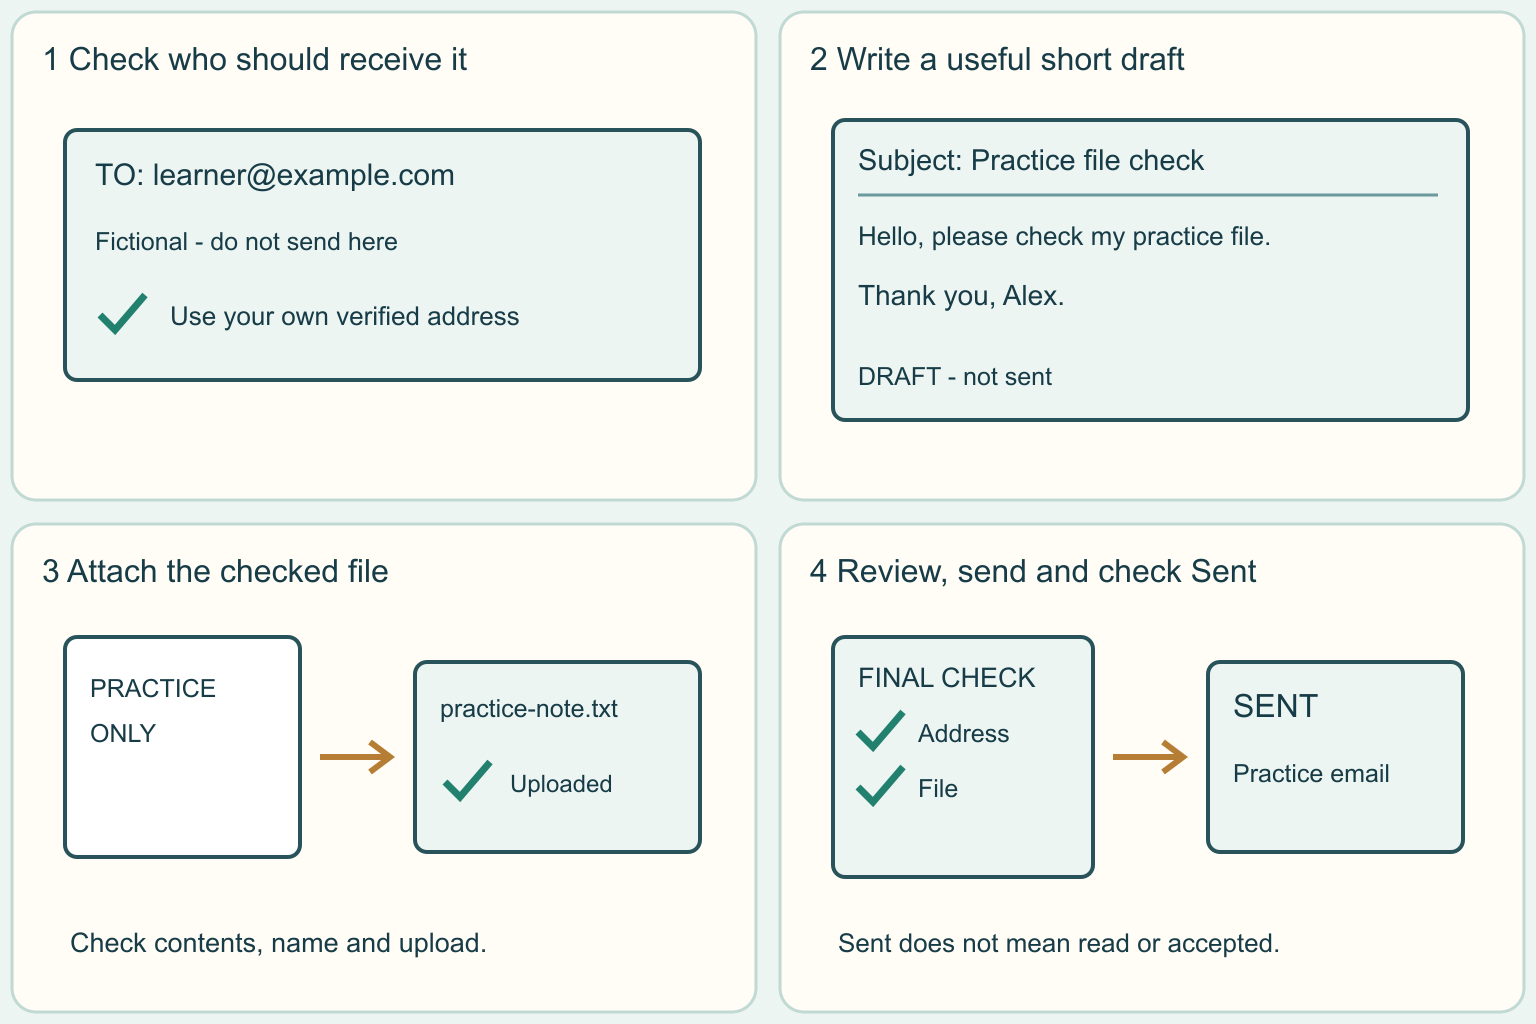
Write a clear email and attach the right file
Practice one short message, check the recipient and attachment, and learn how to confirm it left your drafts.
4 clear steps · checklist & downloadWhat to bring
Admission, financial aid, housing, and parking each have their own office. One upload does not automatically reach all of them.
Prepare the items that apply to your task. For an appointment or application, confirm the receiving organization’s exact requirements. “Ready” means you have reviewed and prepared the item.
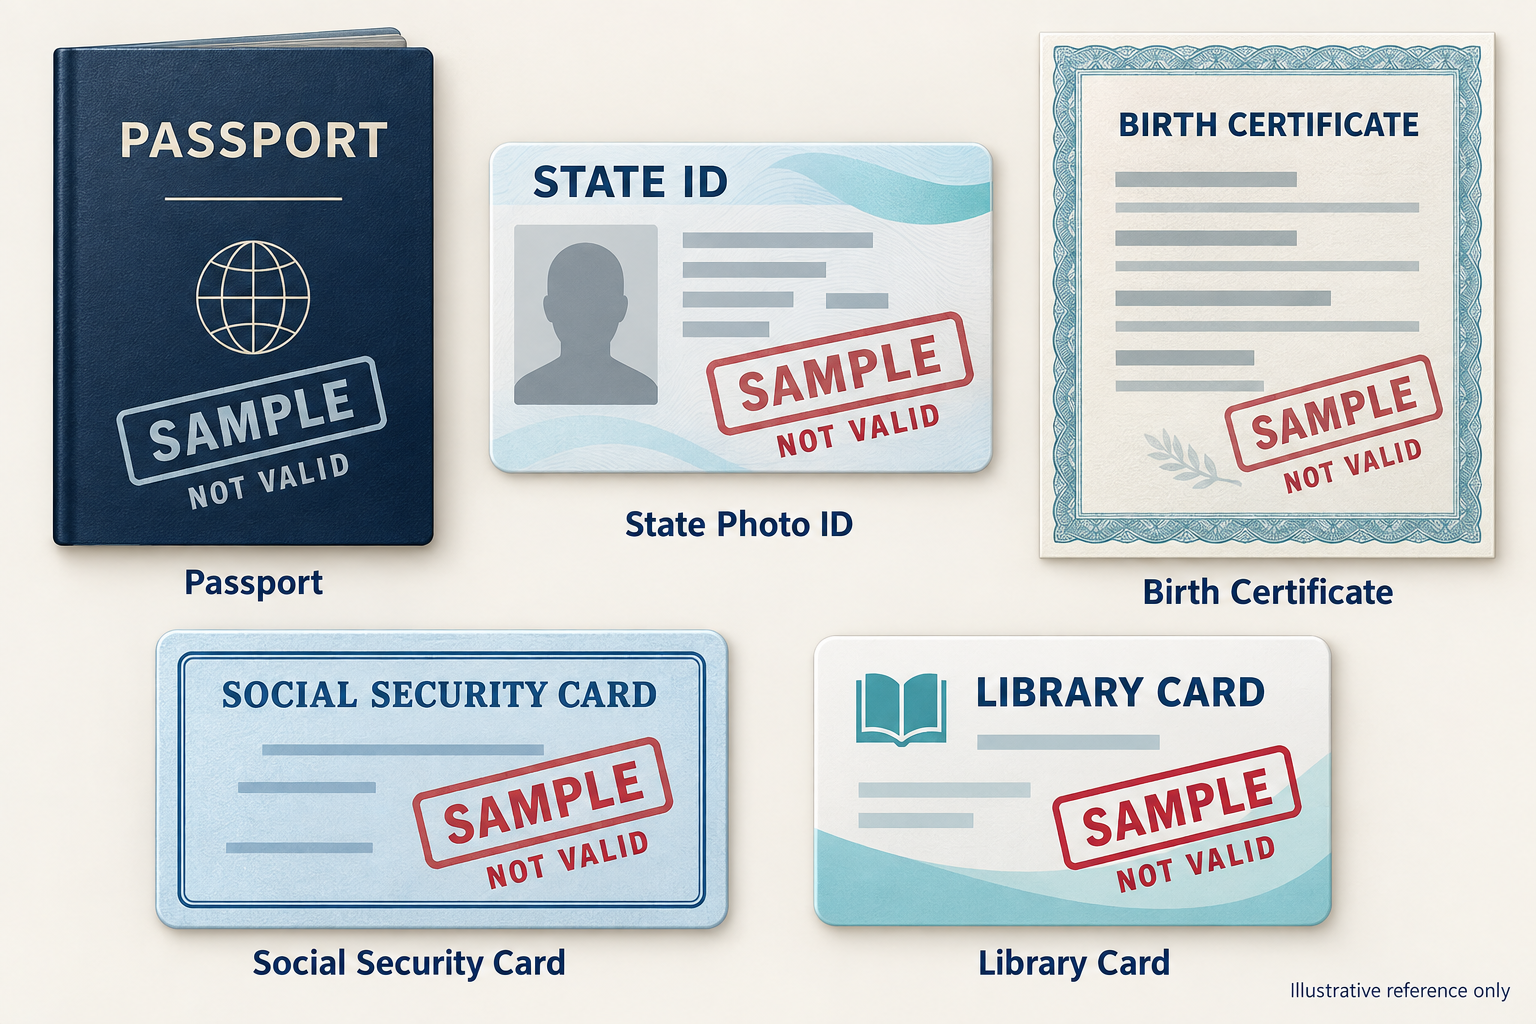
Accepted identification
Why you may need it
Shows who you are. The accepted list depends on the service.
Where to get it
Use a current document you already have, or apply through the state ID agency or other issuing office.
Check before you go
Ask for the exact ID list. A school card, membership card, expired ID, or phone photo may not count.
Transcript, graduation record, and test scores when required
Why you may need it
Shows your schoolwork and any required test results.
Where to get it
Ask your school counselor or registrar for the official transcript process; send scores through the testing organization when required.
Check before you go
Confirm who must send it, whether an unofficial copy is allowed first, and which entry-year policy applies.
Social Security or other tax-ID information, only if required
Why you may need it
Some official financial, school, or employment processes need an identifier.
Where to get it
Use your secure records or the issuing agency’s official process. A replacement Social Security card is free through SSA.
Check before you go
Ask whether only the number is needed and which alternatives apply. Never put full ID numbers or card images into My Vault notes.
FAFSA contributor and financial information
Why you may need it
Supplies information requested for the correct aid year.
Where to get it
Read the current FAFSA instructions with any required contributors; gather the tax-year and asset information it requests.
Check before you go
Each contributor uses their own account and consent. Do not guess which parent qualifies; use the form’s questions.
Aid offer, student number, and housing assignment
Why you may need it
Helps school offices find your record and explain costs.
Where to get it
Use your official student portal.
Check before you go
A loan offer is not gift aid. Read acceptance and housing deadlines.
Contact details and emergency contact
Why you may need it
Lets the organization reach you and, when requested, someone you trust.
Where to get it
Ask the person’s permission and confirm their current phone number and relationship to you.
Check before you go
A contact is not automatically a co-signer, medical decision-maker, or person allowed to collect your records.
Vehicle records: VIN, registration, and title when required
Why you may need it
Identifies the vehicle and shows registration or ownership.
Where to get it
Find the VIN on the car and existing records. Request missing title or registration through your state motor-vehicle office.
Check before you go
A title, registration, and insurance card do different jobs. Bring the specific ones listed for purchase, transfer, renewal, or insurance.
Health, residency, or immigration records, when the school requests them
Why you may need it
May support enrollment, housing, tuition classification, or your particular status.
Where to get it
Ask the relevant school office for its list and approved submission route.
Check before you go
Only supply the records that apply to your program and situation; ask about alternatives or exemptions through that office.
0 of 8 reviewed and prepared. These ticks save in this browser only.
A question you can read aloud
“Which office needs each item, what counts as official, and where can I see that it was received?”
Keep actual documents in a secure place. Do not put Social Security numbers, full account or ID numbers, passwords, or document images into My Vault notes.
See how DMV and Post Office address rules differ →Picture guideSee labeled examples of the things you are learning about.
Words, in plain English
55 terms in College · Open any word to learn more.
Accrued interest and capitalizationAccrued interest is interest that has built up. Capitalization means adding unpaid interest to the loan’s principal when the rules allow it.
How it works
After capitalization, interest may be calculated on a larger principal balance. Not every loan adds interest the same way or at the same time.
A small example
A $1,000 principal plus $40 capitalized interest becomes $1,040 principal. Future interest can then be based on $1,040.
Start here, one step at a time
- Read the interest section for your exact loan type.
- Ask for an example covering school, pauses, and repayment.
- Do not assume no payment due means no interest.
Try explaining this word yourself
Before looking back, explain “Accrued interest and capitalization” in your own words. Which part of the example shows it?
Then compare your explanation with “Accrued interest is interest that has built up. Capitalization means adding unpaid interest to the loan’s principal when the rules allow it.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“When does interest build up, and when could it be added to principal?”
Federal Student Aid: subsidized and unsubsidized loans (opens a new tab)See a labeled picture
ACTA college admission test with English, math, and reading at its core.
How it works
The enhanced ACT composite is based on those three subjects. Science and writing options depend on the test arrangement; confirm school and program requirements before choosing.
A small example
You can compare an official SAT practice test with an official ACT practice test before deciding which to prepare for.
Start here, one step at a time
- Check whether your intended school or scholarship needs particular ACT options.
- Register through ACT and read the instructions for your chosen test format and date.
Try explaining this word yourself
Before looking back, explain “ACT” in your own words. Which part of the example shows it?
Then compare your explanation with “A college admission test with English, math, and reading at its core.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Does this test arrangement include science or writing, and does my intended program need either?”
ACT: enhanced-test questions and answers (opens a new tab)APR — annual percentage rateAPR means annual percentage rate. It helps describe the yearly cost of borrowing.
How it works
Annual means “for one year.” A percentage is a part out of 100. For a mortgage, APR includes interest and certain loan charges. For a credit card, APR usually describes an interest rate, while some fees are separate. There can be different APRs for purchases, cash advances, and late-payment situations. Compare the same kind of borrowing and read all fees.
A small example
A loan with a lower advertised interest rate can still cost more after fees. Compare the actual disclosures.
Start here, one step at a time
- Find the APR and the interest rate in the written offer.
- Compare offers for the same amount and length, including fees and total payments.
Try explaining this word yourself
Before looking back, explain “APR — annual percentage rate” in your own words. Which part of the example shows it?
Then compare your explanation with “APR means annual percentage rate. It helps describe the yearly cost of borrowing.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which fees are included in this APR, and which costs are separate?”
CFPB: mortgage interest rate and APR (opens a new tab)Authorized user vs. co-signerAn authorized user has permission to use a card account. A co-signer promises to repay a debt with the borrower.
How it works
An authorized user is generally not legally responsible for the primary cardholder’s debt merely because they are a user. The account owner is responsible; account reporting may help or hurt a user’s credit. A co-signer is legally responsible for the loan if the borrower does not pay, even if the co-signer never uses the money or car. A joint owner is another role. Read the agreement and ask the lender to explain your exact responsibility.
A small example
A parent lets Alex use a card for groceries: that may be an authorized-user arrangement. The same parent co-signing Alex’s car loan is promising repayment. If Alex misses payments, the parent can owe money and both credit records can be affected.
Start here, one step at a time
- Name the exact role being proposed: card user, joint owner, borrower, or co-signer.
- Ask the issuer who legally owes the debt and how each person’s credit may be affected.
Try explaining this word yourself
Before looking back, explain “Authorized user vs. co-signer” in your own words. Which part of the example shows it?
Then compare your explanation with “An authorized user has permission to use a card account. A co-signer promises to repay a debt with the borrower.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What am I legally responsible for, and how will this affect my credit record?”
CFPB: sharing credit (PDF) (opens a new tab)Birth certificateA government record of a birth, usually listing when and where a person was born and their parents.
How it works
For a U.S. birth, the birth is registered with the responsible vital-records office. A certified copy comes from the state or territory where the birth occurred, sometimes through a local office. A hospital souvenir is not the same thing.
A small example
If you were born in Ohio and now live elsewhere, start with Ohio’s vital-records instructions.
Start here, one step at a time
- Use USAGov’s birth-certificate page to find the correct issuing office.
- Check who may order, accepted ID, fee, and delivery time.
- For a birth abroad, use the separate consular-record or foreign-record route that fits your birth.
Try explaining this word yourself
Before looking back, explain “Birth certificate” in your own words. Which part of the example shows it?
Then compare your explanation with “A government record of a birth, usually listing when and where a person was born and their parents.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“How do I prove I may request this record, and is this the certified version I need?”
USAGov: get a certified birth certificate (opens a new tab)See a labeled picture
Borrower and lenderThe borrower takes a loan. The lender gives the loan and expects repayment.
How it works
A loan servicer may be a different company that sends bills and handles payments. An adviser or salesperson is not automatically the lender.
A small example
If a bank lends you $500, you are the borrower and the bank is the lender.
Start here, one step at a time
- Find both names on the agreement.
- Use verified contact details on official statements.
- Keep any notice of a servicer change.
Try explaining this word yourself
Before looking back, explain “Borrower and lender” in your own words. Which part of the example shows it?
Then compare your explanation with “The borrower takes a loan. The lender gives the loan and expects repayment.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Who lends the money, who sends the bill, and who do I contact about a problem?”
FTC: understanding your credit (opens a new tab)See a labeled picture
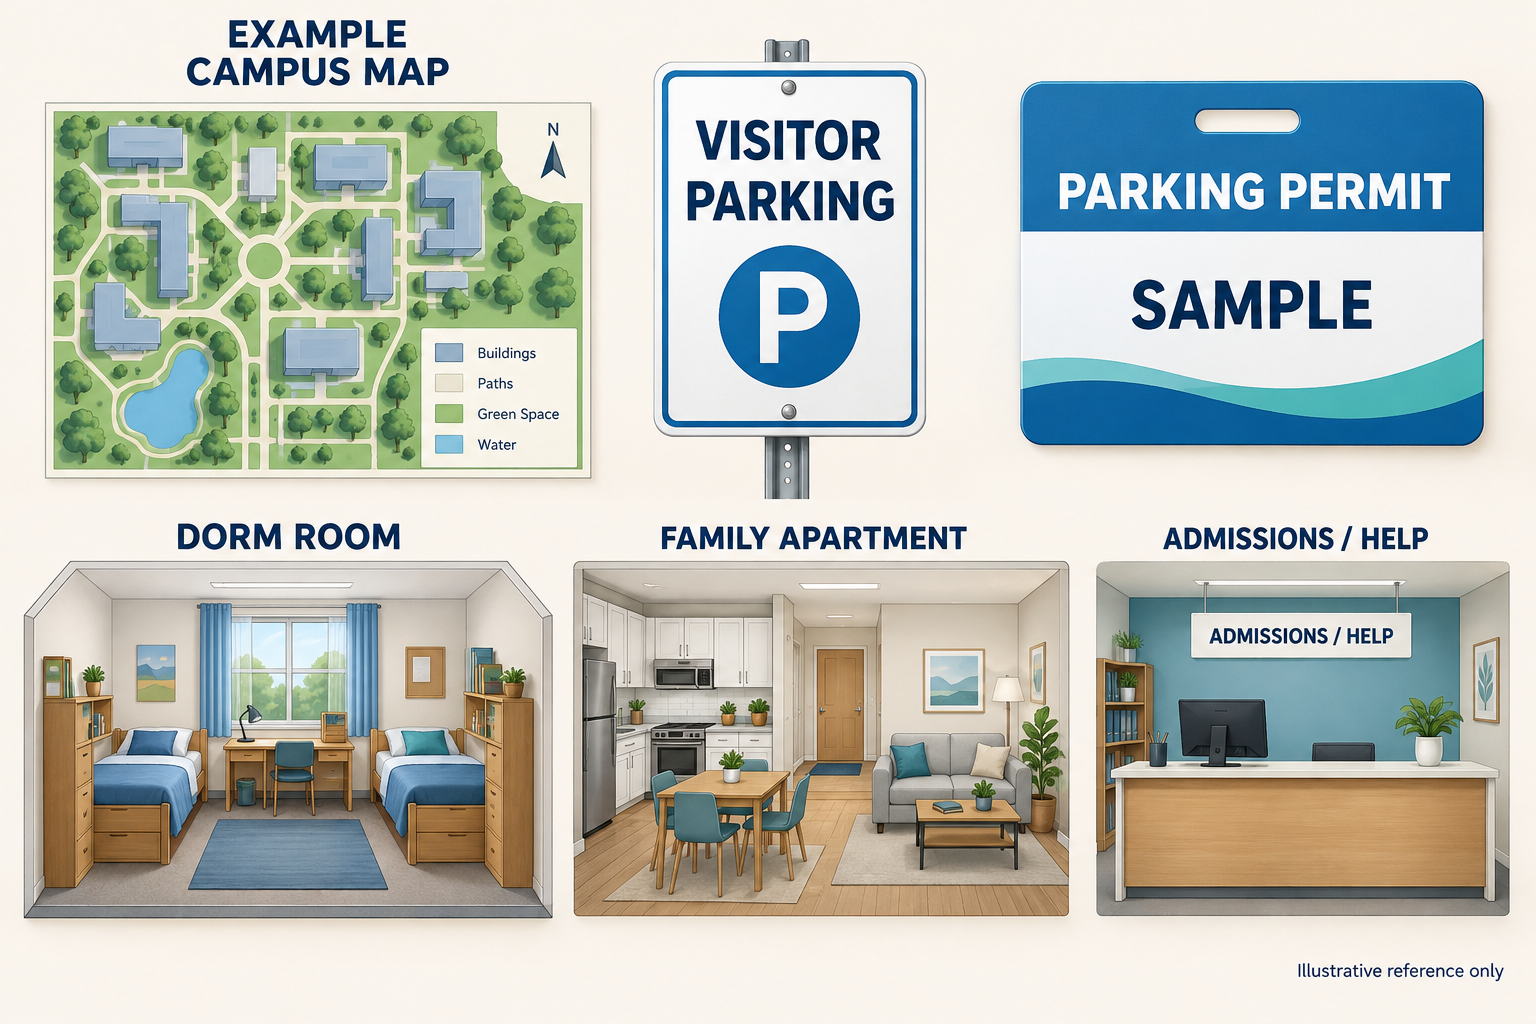
Campus map and building codeA campus map shows school buildings and routes. A building code is a short name used on a schedule.
How it works
Your schedule may say “SCI 204.” That could mean Science Building, room 204. Schools choose their own codes. A map may have separate views for parking and accessible entrances.
A small example
Two campuses can each have a Science Building. Use the campus address printed on your actual class schedule.
Start here, one step at a time
- Search your school’s official website for “campus map.”
- Choose the correct campus. Download its offered PDF, or save/print the official map if permitted.
- Mark your buildings, parking or bus stop, and help desk. Walk the route before the first class.
Try explaining this word yourself
Before looking back, explain “Campus map and building code” in your own words. Which part of the example shows it?
Then compare your explanation with “A campus map shows school buildings and routes. A building code is a short name used on a schedule.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Where is the official map for my campus, and which entrance can I use?”
Example: CU Boulder official campus map (use your own school’s map) (opens a new tab)See a labeled picture
Campus parking permitPermission to park a certain vehicle in certain school parking areas under stated rules.
How it works
A permit may be a sticker, hanging tag, or license plate registered online. It may work only in named zones and hours. It usually does not promise an open space.
A small example
A commuter permit for lot C does not automatically allow parking in a resident lot or an accessible space.
Start here, one step at a time
- On the official school site, search “parking and transportation.”
- Read student, commuter, resident, visitor, and accessible-parking rules. Look up the map legend.
- Use the department’s official contact page or school directory to find its phone number. Ask before paying for a permit.
Try explaining this word yourself
Before looking back, explain “Campus parking permit” in your own words. Which part of the example shows it?
Then compare your explanation with “Permission to park a certain vehicle in certain school parking areas under stated rules.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which permit fits my classes and housing, and where may I park at these times?”
Example: CU Boulder parking office and maps (opens a new tab)See a labeled picture
Collateral and secured loanCollateral is property a lender can claim through the applicable process if the borrower does not repay a secured loan.
How it works
A car can secure an auto loan. A home can secure a mortgage. An unsecured loan has no named collateral but is still a debt you must repay.
A small example
Missing payments on a car loan can put the car at risk. It is not just a late-fee issue.
Start here, one step at a time
- Look for “security interest” or “collateral” in the agreement.
- Ask what happens after a missed payment.
- Do not pledge property you do not understand you are risking.
Try explaining this word yourself
Before looking back, explain “Collateral and secured loan” in your own words. Which part of the example shows it?
Then compare your explanation with “Collateral is property a lender can claim through the applicable process if the borrower does not repay a secured loan.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which property secures this loan, and what can happen if I miss payments?”
FTC: understanding your credit (opens a new tab)See a labeled picture
College credit hoursCollege credits are units that count how much a course adds toward a degree.
How it works
A three-credit class adds three credits when you earn credit under the school’s rules. Credits are not money and are unrelated to a credit score. Many traditional three-credit courses meet about three hours weekly and expect additional work outside class, but labs, online courses, and short terms differ. Credits also affect tuition and full-time status. Ask your school about your program and aid rules.
A small example
Four three-credit courses equal 12 credits. If each meets for three hours and you plan six hours of outside work per course, that is 12 + 24 = 36 hours a week in this example. Your actual workload can differ. A 120-credit degree needs the right required courses, not just any 120 credits.
Start here, one step at a time
- Open your program’s degree plan with an adviser.
- List each course’s credits and weekly class/study time before choosing a manageable schedule.
Try explaining this word yourself
Before looking back, explain “College credit hours” in your own words. Which part of the example shows it?
Then compare your explanation with “College credits are units that count how much a course adds toward a degree.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Will these courses count toward my program, and will they transfer where I plan to go?”
Cost of attendance and net priceCost of attendance is a school’s estimate of school and living costs. Net price is that estimate minus grants and scholarships.
How it works
Tuition is only one part. Cost of attendance can include fees, housing, food, books, transport, and other allowed costs. Some go on the school bill; others are paid elsewhere. The estimate can differ from your own spending. Net price shows what remains to fund before loans or work. A loan pays a bill now but creates debt; it is not a discount.
A small example
Tuition/fees $10,000 + living and other costs $14,000 = $24,000. Subtract $9,000 in grants/scholarships: net price is $15,000. If you borrow $5,000, you still need to fund $10,000 now and later repay the loan under its terms.
Start here, one step at a time
- Use the school’s cost of attendance for your actual housing plan.
- Subtract grants and scholarships only. Keep loans and expected job earnings on separate lines.
Try explaining this word yourself
Before looking back, explain “Cost of attendance and net price” in your own words. Which part of the example shows it?
Then compare your explanation with “Cost of attendance is a school’s estimate of school and living costs. Net price is that estimate minus grants and scholarships.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which costs are estimates, and which aid does not have to be repaid?”
Federal Student Aid: understand aid offers (opens a new tab)Deferment and forbearanceApproved ways to pause or reduce payments under certain loan rules.
How it works
A pause is not forgiveness. Interest may continue. Eligibility, duration, and consequences differ, so get the servicer’s written terms before relying on a pause.
A small example
If payments stop for a month but interest continues, the debt may still grow.
Start here, one step at a time
- Contact the actual servicer before you stop paying.
- Ask about the options available for your loan.
- Keep the approval and restart date.
Try explaining this word yourself
Before looking back, explain “Deferment and forbearance” in your own words. Which part of the example shows it?
Then compare your explanation with “Approved ways to pause or reduce payments under certain loan rules.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Would interest continue, and what happens when the pause ends?”
Federal Student Aid: financial-aid words (opens a new tab)See a labeled picture
Dorm or residence hallSchool-managed housing where students live during school.
How it works
You may share a bedroom or bathroom. A contract may cover school terms rather than a full year. Meal plans, breaks, guests, room changes, and move-in dates have rules.
A small example
A room costing $3,000 for a semester is not necessarily available during winter break.
Start here, one step at a time
- Open the school’s Housing or Residence Life page.
- Read eligibility, room choices, the contract, and the official packing list.
- Confirm the deadline, deposit, meal-plan rules, and key pickup location.
Try explaining this word yourself
Before looking back, explain “Dorm or residence hall” in your own words. Which part of the example shows it?
Then compare your explanation with “School-managed housing where students live during school.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What is included, what is shared, and where can I stay during breaks?”
Example: CU Boulder housing options (opens a new tab)See a labeled picture
Emergency contactA person an organization should try to reach if you need urgent help.
How it works
Choose someone who agrees to be contacted and can usually answer. Give the requested name, relationship, and phone number. Schools, employers, and clinics keep separate records. This does not by itself make the person a legal guardian, medical decision-maker, co-signer, or beneficiary.
A small example
You list your aunt at college with her permission. If the school needs to reach someone about an emergency, it can call her. That does not let her sign a loan for you.
Start here, one step at a time
- Ask someone dependable whether you may list them.
- Confirm their number, enter it separately at school and work, and update it when it changes.
Try explaining this word yourself
Before looking back, explain “Emergency contact” in your own words. Which part of the example shows it?
Then compare your explanation with “A person an organization should try to reach if you need urgent help.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Who should be contacted first, and what should they know?”
Ready.gov: household preparation (opens a new tab)Extra principal payment / prepaymentPaying some or all of a loan earlier than scheduled.
How it works
Extra money may reduce principal, but you need to know how the servicer applies it. Check for restrictions or penalties. Paying ahead on a due date is not always the same as reducing principal as intended.
A small example
An extra $50 meant for principal should be checked on the next statement to see where it went.
Start here, one step at a time
- Read the agreement’s early-payment rules.
- Use the servicer’s designated instructions.
- Confirm the new balance and keep your normal payment obligations clear.
Try explaining this word yourself
Before looking back, explain “Extra principal payment / prepayment” in your own words. Which part of the example shows it?
Then compare your explanation with “Paying some or all of a loan earlier than scheduled.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“How do I direct extra money to principal, and is there any penalty?”
CFPB: buying a home (opens a new tab)See a labeled picture
FAFSAFAFSA means Free Application for Federal Student Aid. It is a free form used to ask for help paying for education.
How it works
You submit information about yourself and, when required, other contributors. Federal Student Aid processes it and sends information to the schools you list. Schools use it with their own rules to prepare aid offers. Completing the FAFSA is not applying for admission, accepting a loan, or promising that a parent will pay. Complete the correct academic year and check federal, state, and school deadlines.
A small example
You submit the form for a coming school year, review its summary, and later receive a school’s offer showing grants, work-study, and possibly loans. You still decide what to accept and complete any follow-up tasks.
Start here, one step at a time
- Choose the correct school year on StudentAid.gov and use your own account.
- Invite any required contributors, supply consent and information, submit, and check the processed summary and school requests.
Try explaining this word yourself
Before looking back, explain “FAFSA” in your own words. Which part of the example shows it?
Then compare your explanation with “FAFSA means Free Application for Federal Student Aid. It is a free form used to ask for help paying for education.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which year’s form do I need, who must contribute information, and what are my deadlines?”
Federal Student Aid: FAFSA starting steps (opens a new tab)FAFSA contributorA person required to provide information on your FAFSA form.
How it works
Depending on your situation, a contributor may be a parent or spouse. Each uses their own StudentAid.gov account. Giving information does not by itself make that person responsible for paying your school bill or taking out a loan.
A small example
A parent may need to provide information even if they do not plan to pay your tuition.
Start here, one step at a time
- Use the questions in the official form to learn who is required.
- Invite the correct person using the form’s process. Do not share account passwords.
- Ask the aid office for help with unusual family circumstances instead of guessing answers.
Try explaining this word yourself
Before looking back, explain “FAFSA contributor” in your own words. Which part of the example shows it?
Then compare your explanation with “A person required to provide information on your FAFSA form.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Who must contribute to my form, and what can I do if I cannot safely contact them?”
Federal Student Aid: FAFSA starting steps (opens a new tab)See a labeled picture
Family or graduate student housingHousing a school may set aside for eligible students with partners, children, or certain graduate-student situations.
How it works
Not every school offers it. Eligibility, waitlists, household rules, and lease length vary. Do not assume an ordinary dorm allows family members to live there.
A small example
A school may have a small number of family apartments and a long waitlist. Applying does not promise a unit.
Start here, one step at a time
- Look for “family housing” on the school’s official housing website.
- Ask what proof of student status and household eligibility is required.
- Compare the full price with available off-campus options.
Try explaining this word yourself
Before looking back, explain “Family or graduate student housing” in your own words. Which part of the example shows it?
Then compare your explanation with “Housing a school may set aside for eligible students with partners, children, or certain graduate-student situations.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Who is eligible, who may live with me, and how long is the wait?”
Example: CU Boulder housing options (opens a new tab)See a labeled picture
Finance charge and total of paymentsFinance charge describes certain dollar costs of credit. Total of payments is the total of scheduled payments shown in a disclosure.
How it works
Neither term means just the cash borrowed. Read what the disclosure includes and excludes. A late fee or future rate change may affect what you actually pay.
A small example
If scheduled payments total $1,200 for $1,000 financed, the difference is $200 in this simplified example.
Start here, one step at a time
- Find both dollar amounts on the offer.
- Compare offers using the same borrowed amount and term.
- Ask about variable rates and extra fees.
Try explaining this word yourself
Before looking back, explain “Finance charge and total of payments” in your own words. Which part of the example shows it?
Then compare your explanation with “Finance charge describes certain dollar costs of credit. Total of payments is the total of scheduled payments shown in a disclosure.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What is included in these totals, and what could make the actual cost different?”
CFPB: read a Loan Estimate (opens a new tab)See a labeled picture
Financial-aid offerThe school’s written list of aid it is offering you.
How it works
The list may mix gifts, loans, and work-study. Gifts can lower the price. Loans must be repaid. Work-study requires you to get a job and earn wages. Read each line separately.
A small example
“$10,000 in aid” might mean $4,000 in grants and $6,000 in loans. That is not a $10,000 discount.
Start here, one step at a time
- Open the offer in the school’s official student portal.
- Mark each line grant, scholarship, loan, or work-study.
- Ask about anything unclear before accepting a loan.
Try explaining this word yourself
Before looking back, explain “Financial-aid offer” in your own words. Which part of the example shows it?
Then compare your explanation with “The school’s written list of aid it is offering you.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which lines are free aid, which are debt, and what must I do to accept each one?”
Federal Student Aid: understand aid offers (opens a new tab)See a labeled picture
Government photo IDA card or document from a government that has your name and picture.
How it works
Examples include a state ID, driver’s license, or passport. The place checking your identity decides which documents it accepts. An expired card or a phone photo may not qualify.
A small example
A library may accept a school ID under its rules. An airport uses a different list.
Start here, one step at a time
- Find the office’s official list for the service you need.
- Compare your document’s name and expiration date with that list.
- Bring the required physical document; ask before relying on a phone copy.
Try explaining this word yourself
Before looking back, explain “Government photo ID” in your own words. Which part of the example shows it?
Then compare your explanation with “A card or document from a government that has your name and picture.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which exact IDs do you accept for this service, and must they be unexpired?”
USAGov: official document replacements (opens a new tab)See a labeled picture
GPA — grade point averageGPA means grade point average: a number that summarizes your grades.
How it works
Your school gives grades number values, then averages them using its rules. A common unweighted scale uses A = 4, B = 3, C = 2, D = 1, and F = 0. Weighted scales may add points for harder courses; schools differ. Colleges may recalculate GPA. It can affect admission, scholarships, program entry, and staying eligible, but it is only one part of a decision.
A small example
In four equal-weight classes, an A, B, B, and C give (4 + 3 + 3 + 2) ÷ 4 = 3.0 on that example scale. A lower GPA may close some options today; an adviser can help you plan tutoring, stronger future grades, or another entry route.
Start here, one step at a time
- Ask your counselor for your transcript and the school’s GPA scale.
- Check requirements for the college, program, or scholarship you want; ask about support and improvement options.
Try explaining this word yourself
Before looking back, explain “GPA — grade point average” in your own words. Which part of the example shows it?
Then compare your explanation with “GPA means grade point average: a number that summarizes your grades.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Is this GPA weighted, and how does this college recalculate it?”
GrantMoney given for school that you usually do not pay back if you follow the award rules.
How it works
Many grants are based on financial need. This means the program looks at your financial situation. A government, school, or other group may provide the money. A grant is not a loan.
A small example
A $1,000 grant can cover $1,000 of allowed school costs. You usually do not owe that $1,000 later. Leaving school or not meeting conditions can change that.
Start here, one step at a time
- Start with the free FAFSA at StudentAid.gov for federal aid.
- Ask your school’s financial-aid office about state and school grants, other forms, and deadlines.
- Read the award’s rules about classes, attendance, grades, and renewal.
Try explaining this word yourself
Before looking back, explain “Grant” in your own words. Which part of the example shows it?
Then compare your explanation with “Money given for school that you usually do not pay back if you follow the award rules.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which costs can this grant pay, and what could make me repay some of it?”
Federal Student Aid: grants (opens a new tab)See a labeled picture
Grant vs. scholarshipBoth can help pay for school without the usual promise to repay a loan, if you meet their conditions.
How it works
Grants often depend on financial need. Scholarships may use grades, talent, service, background, financial need, or other rules. The words overlap, so read the actual award. Check allowed expenses, renewal, enrollment, grade rules, and what happens if you withdraw or receive too much aid. Open the separate Grant and Scholarship entries for application steps.
A small example
A $1,000 scholarship and a $1,000 grant can both reduce what you must fund by $1,000. Neither label alone promises the award repeats next year.
Start here, one step at a time
- Ask the school financial-aid office about grants and scholarships separately.
- Write each award’s deadline, application, allowed uses, renewal, and repayment conditions.
Try explaining this word yourself
Before looking back, explain “Grant vs. scholarship” in your own words. Which part of the example shows it?
Then compare your explanation with “Both can help pay for school without the usual promise to repay a loan, if you meet their conditions.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Is this renewable, and what must I do each year to keep it?”
Federal Student Aid: understand aid offers (opens a new tab)Installment and payment scheduleAn installment is one of a series of payments. The schedule says when each payment is due.
How it works
A payment may cover interest, principal, or fees. Weekly and monthly schedules are different. Check the first and final payments, which may differ from the others.
A small example
Twelve monthly $50 payments add up to $600. That is different from twelve weekly payments.
Start here, one step at a time
- Count the scheduled payments.
- Add fees that are not included in them.
- Put due dates beside your paydays.
Try explaining this word yourself
Before looking back, explain “Installment and payment schedule” in your own words. Which part of the example shows it?
Then compare your explanation with “An installment is one of a series of payments. The schedule says when each payment is due.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“How many payments are there, on which dates, and is the last one larger?”
CFPB: credit-card contract terms (opens a new tab)See a labeled picture
Interest rateThe percentage used to calculate the charge for borrowing money.
How it works
The stated annual rate is not usually charged all at once. The balance, time, calculation method, and payment schedule affect the dollars charged. It excludes some other costs of borrowing.
A small example
With simple interest for one full year, $1,000 × 6% = $60. A shrinking balance changes the result.
Start here, one step at a time
- Turn a percent into a decimal by dividing by 100: 6% is 0.06.
- Ask which balance and time period the lender uses before calculating the charge.
Try explaining this word yourself
Before looking back, explain “Interest rate” in your own words. Which part of the example shows it?
Then compare your explanation with “The percentage used to calculate the charge for borrowing money.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Is this rate fixed or variable, and how is interest calculated?”
CFPB: mortgage interest rate and APR (opens a new tab)Late fee and missed paymentA late fee is a charge that may apply when a required payment is late.
How it works
A missed payment can also lead to interest, collection steps, or credit-report effects. The timing is not identical for each consequence. A late-fee grace period is not permission to ignore the due date.
A small example
A bill due on the 10th is still due on the 10th even if a fee is not charged immediately.
Start here, one step at a time
- Check the due date and payment-processing time.
- Contact the lender early through a verified number if you may miss it.
- Keep any written payment arrangement.
Try explaining this word yourself
Before looking back, explain “Late fee and missed payment” in your own words. Which part of the example shows it?
Then compare your explanation with “A late fee is a charge that may apply when a required payment is late.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“When is a payment considered received, and what help is available if I cannot pay?”
CFPB: credit-card contract terms (opens a new tab)See a labeled picture
Library cardA card or account that lets you use a particular library’s services.
How it works
It may let you borrow books, use computers, or download materials. Public libraries set their own residency, age, and proof rules. It is not a general substitute for an accepted government photo ID.
A small example
A free library card may give you access to e-books. Some services or late/lost-item charges depend on the library.
Start here, one step at a time
- Find your local library through its official website.
- Open “Get a library card” or call the desk.
- Bring the listed documents and ask staff to show you one service you want to use.
Try explaining this word yourself
Before looking back, explain “Library card” in your own words. Which part of the example shows it?
Then compare your explanation with “A card or account that lets you use a particular library’s services.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What do I need to join, which services are free, and does a minor need an adult?”
USAGov: find your public library (opens a new tab)See a labeled picture
LoanMoney you borrow and agree to pay back.
How it works
The borrower receives the money. The lender provides it. Interest is a charge for borrowing. Fees are other charges. A loan can cost more than the amount you receive.
A small example
Borrow $100 and agree to repay $110. The extra $10 is a borrowing cost. This is a simple made-up example, not a loan offer.
Start here, one step at a time
- Write down the amount you receive.
- Find every payment and fee in the written offer.
- Compare the repayment dates with your own budget before signing.
Try explaining this word yourself
Before looking back, explain “Loan” in your own words. Which part of the example shows it?
Then compare your explanation with “Money you borrow and agree to pay back.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“How much will I receive, and how much will I repay in total?”
FTC: understanding your credit (opens a new tab)See a labeled picture
Loan termThe length of time the loan is scheduled to last.
How it works
A longer term may reduce the required payment but can increase total interest. Compare the total repaid, not just the monthly amount.
A small example
30 years × 12 months = 360 monthly payments. Fifteen years means 180.
Start here, one step at a time
- Convert years to months by multiplying by 12.
- Compare the monthly payment and total repayment at each offered length.
Try explaining this word yourself
Before looking back, explain “Loan term” in your own words. Which part of the example shows it?
Then compare your explanation with “The length of time the loan is scheduled to last.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What is the payment and total repayment at each term?”
CFPB: buying a home (opens a new tab)Major, degree, and certificateA major is your main subject. A degree or certificate is an award for finishing a program’s required work.
How it works
A certificate often focuses on a specific skill. Associate and bachelor’s degrees are different kinds of college awards. The credits, time, cost, and job requirements vary.
A small example
Biology can be a major within a bachelor’s degree. Taking one biology class does not mean you have earned the degree.
Start here, one step at a time
- Find the official program page.
- Read its required courses and completion requirements.
- Ask an academic adviser which courses to take first.
Try explaining this word yourself
Before looking back, explain “Major, degree, and certificate” in your own words. Which part of the example shows it?
Then compare your explanation with “A major is your main subject. A degree or certificate is an award for finishing a program’s required work.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which award does this program lead to, and does it meet the requirements for the job I want?”
USAGov: kinds of student aid (opens a new tab)See a labeled picture
Minimum paymentThe smallest required payment for the billing period under the account terms.
How it works
Making the minimum does not mean you have paid off the debt or avoided interest. Continued purchases, fees, and interest can make payoff much slower.
A small example
Paying $25 toward a $500 balance leaves debt; the exact next balance also depends on interest and new activity.
Start here, one step at a time
- Find the minimum and due date on the statement.
- Read the payoff warning and budget a larger payment if you can; contact the issuer early if you cannot pay.
Try explaining this word yourself
Before looking back, explain “Minimum payment” in your own words. Which part of the example shows it?
Then compare your explanation with “The smallest required payment for the billing period under the account terms.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What would happen if I paid only the minimum, and where is the payoff information?”
CFPB: credit-card contract terms (opens a new tab)Off-campus living and apartment livingOff-campus means outside school-managed housing. An apartment is one type of home you can rent.
How it works
An off-campus home can be an apartment, a room, or a house. You may sign a lease with a private owner and pay utilities yourself. A school listing does not always mean the school owns or guarantees the home.
A small example
A 12-month lease can require summer rent even if your classes last only nine months.
Start here, one step at a time
- Compare school housing and private rentals over the same number of months.
- Include travel, utilities, furniture, food, and deposits.
- Follow the First Apartment path before signing a private lease.
Try explaining this word yourself
Before looking back, explain “Off-campus living and apartment living” in your own words. Which part of the example shows it?
Then compare your explanation with “Off-campus means outside school-managed housing. An apartment is one type of home you can rent.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Who manages this home, how long is the lease, and what is the total cost?”
USAGov: state tenant-rights resources (opens a new tab)See a labeled picture
Origination fee and amount financedAn origination fee is a charge for making a loan. Amount financed is a disclosure figure for credit provided, calculated under the applicable rules.
How it works
A fee may be paid upfront, taken from the amount sent to you, or added to the loan. These arrangements change the cash you get and what you owe.
A small example
A $1,000 loan with a $50 fee taken out sends you $950, but you may still owe $1,000 plus interest.
Start here, one step at a time
- Compare cash received with the loan balance.
- Ask whether a fee is included in APR.
- Do not count a withheld fee as money available to spend.
Try explaining this word yourself
Before looking back, explain “Origination fee and amount financed” in your own words. Which part of the example shows it?
Then compare your explanation with “An origination fee is a charge for making a loan. Amount financed is a disclosure figure for credit provided, calculated under the applicable rules.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“How much reaches me after fees, and what balance will I repay?”
CFPB: read a Loan Estimate (opens a new tab)See a labeled picture
Passport book and passport cardA U.S. passport proves U.S. citizenship and identity for specified travel uses.
How it works
The book is used for international air travel. The card has limited land and sea uses and cannot replace the book for international flights. A passport does not replace a required visa or guarantee entry.
A small example
For a flight abroad, check passport-book and destination entry rules before buying nonrefundable travel.
Start here, one step at a time
- Open the State Department’s passport site and select your age and situation.
- Follow the correct application or renewal route, photo rules, evidence list, and fee instructions.
- Allow processing plus mailing time; check the current timeline before setting travel dates.
Try explaining this word yourself
Before looking back, explain “Passport book and passport card” in your own words. Which part of the example shows it?
Then compare your explanation with “A U.S. passport proves U.S. citizenship and identity for specified travel uses.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which passport type and validity period does my trip require?”
U.S. State Department: passport applications (opens a new tab)See a labeled picture
Past due, default, and collectionsPast due means a required payment is late. Default is a more serious contract status. Collections means efforts to recover a claimed debt.
How it works
Timing and consequences differ by agreement and law. Verify unexpected debt claims and get help understanding notices rather than ignoring them or sending money to an unverified caller.
A small example
A text claiming you owe money is not enough to establish that the debt or sender is legitimate.
Start here, one step at a time
- Verify the collector and the debt information before sending money.
- Keep notices and ask about your rights and deadlines using the official consumer-help resources.
Try explaining this word yourself
Before looking back, explain “Past due, default, and collections” in your own words. Which part of the example shows it?
Then compare your explanation with “Past due means a required payment is late. Default is a more serious contract status. Collections means efforts to recover a claimed debt.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Can you provide the required details about this claimed debt through a verified process?”
FTC: understanding your credit (opens a new tab)PrerequisiteA class or requirement you must finish before starting another class.
How it works
Schools use prerequisites to make sure you have the starting skills. A placement result or approved transfer course may sometimes meet a requirement. Ask before enrolling.
A small example
Algebra may need to come before a higher math course. The exact rule belongs to that school.
Start here, one step at a time
- Open the course description in the college catalog.
- Look for “prerequisite” and “corequisite.” A corequisite is taken at the same time.
- Have an adviser confirm your plan.
Try explaining this word yourself
Before looking back, explain “Prerequisite” in your own words. Which part of the example shows it?
Then compare your explanation with “A class or requirement you must finish before starting another class.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What must I finish before I can take this class?”
USAGov: kinds of student aid (opens a new tab)See a labeled picture
PrincipalThe part of a loan balance that is borrowed money, before interest and other charges.
How it works
A payment may be split between interest and reducing principal. Paying $1,000 does not necessarily lower the loan balance by $1,000.
A small example
If a $300 payment contains $80 interest and $220 principal, the principal falls by $220.
Start here, one step at a time
- Find “principal balance” on the loan statement.
- Look at the last payment breakdown: interest and fees do not reduce principal.
Try explaining this word yourself
Before looking back, explain “Principal” in your own words. Which part of the example shows it?
Then compare your explanation with “The part of a loan balance that is borrowed money, before interest and other charges.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“How much of this payment reduces the balance?”
CFPB: read a Loan Estimate (opens a new tab)Promissory note / loan agreementThe document in which a borrower promises to repay a loan under its rules.
How it works
It names the people or organizations involved and explains repayment. An electronic signature can create a real obligation. A FAFSA form and a promissory note do different jobs.
A small example
Accepting a school place does not by itself explain the terms of a separate private loan. Read that loan’s agreement too.
Start here, one step at a time
- Find the loan amount, interest rules, fees, due dates, and repayment rules.
- Ask for each unfamiliar word to be explained.
- Keep the final signed agreement securely.
Try explaining this word yourself
Before looking back, explain “Promissory note / loan agreement” in your own words. Which part of the example shows it?
Then compare your explanation with “The document in which a borrower promises to repay a loan under its rules.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What exactly am I promising, and can I take a copy to read before signing?”
Federal Student Aid: financial-aid words (opens a new tab)See a labeled picture
RefinancingReplacing an existing loan with a new loan.
How it works
A new rate, term, fee, or lender can change the total cost. A lower monthly payment can still cost more over a longer period. Replacing federal student debt with private debt can remove federal benefits.
A small example
A $200 payment for 36 months totals $7,200. A $150 payment for 60 months totals $9,000, before any extra fees.
Start here, one step at a time
- Compare remaining old payments with all new payments and fees.
- Ask what protections would be lost.
- Do not decide using the monthly payment alone.
Try explaining this word yourself
Before looking back, explain “Refinancing” in your own words. Which part of the example shows it?
Then compare your explanation with “Replacing an existing loan with a new loan.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What total cost and benefits change if I replace this loan?”
CFPB: student-loan co-signers (opens a new tab)See a labeled picture
Roommate agreementA written plan between the people sharing a home.
How it works
Set out each person’s bill share, chores, guests, and what happens if someone leaves. This does not replace the lease or change what the landlord can require under it.
A small example
Splitting $1,200 three ways gives $400 each if you agree on equal shares. Other bills still need a plan.
Start here, one step at a time
- Discuss bills, chores, guests, and leaving early before moving in.
- Write and share the agreement, then compare it with everyone’s lease duties.
Try explaining this word yourself
Before looking back, explain “Roommate agreement” in your own words. Which part of the example shows it?
Then compare your explanation with “A written plan between the people sharing a home.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Whose name is on each bill, and how will we prove it was paid?”
USAGov: state tenant-rights resources (opens a new tab)SATA college admission test from College Board covering Reading and Writing, and Math.
How it works
The digital SAT uses the Bluebook app on an approved device. Whether you need a score depends on each school, program, and scholarship. Start with their current requirements.
A small example
Taking the SAT does not apply to a college for you. Registration, score sending, and college applications are separate tasks.
Start here, one step at a time
- Check your colleges’ current test rules before registering.
- Use College Board’s official account, registration, practice, and device-check instructions.
Try explaining this word yourself
Before looking back, explain “SAT” in your own words. Which part of the example shows it?
Then compare your explanation with “A college admission test from College Board covering Reading and Writing, and Math.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Does my intended college require, accept, or ignore SAT scores for my entry year?”
College Board: how the SAT is structured (opens a new tab)Scaled score and percentileA scaled score reports performance on a test’s scoring system; a percentile compares results with a reference group.
How it works
Neither is simply your percentage of questions correct. Read which group and year a percentile describes. SAT and ACT use different scales.
A small example
A 70th percentile means roughly 70% of that comparison group scored at or below that result; it does not mean 70% correct.
Start here, one step at a time
- Open the official score report and read its scale.
- Use section feedback to choose a specific skill to practice next.
Try explaining this word yourself
Before looking back, explain “Scaled score and percentile” in your own words. Which part of the example shows it?
Then compare your explanation with “A scaled score reports performance on a test’s scoring system; a percentile compares results with a reference group.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which comparison group is used, and what do my section scores suggest I should practice?”
College Board: understand SAT scores (opens a new tab)ScholarshipMoney awarded to help pay for school. You usually keep it without repayment if you meet its rules.
How it works
An award may be based on grades, a skill, service, financial need, a major, or other criteria. Criteria means the rules for who may apply. Scholarships and grants can overlap; the award’s written rules matter more than its name.
A small example
A local group offers $500 for approved books and tuition. You apply, are chosen, and send proof that you enrolled. That does not mean every student who applies gets $500.
Start here, one step at a time
- Ask your counselor and the college aid office for their scholarship lists.
- Check a community foundation, your employer, and your family’s employers. Read who can apply.
- Gather the requested essay, transcript, references, and proof of enrollment. Submit by the deadline and keep confirmation.
Try explaining this word yourself
Before looking back, explain “Scholarship” in your own words. Which part of the example shows it?
Then compare your explanation with “Money awarded to help pay for school. You usually keep it without repayment if you meet its rules.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Do I need a separate application, and is this award for one year or every year?”
Federal Student Aid: find and apply for scholarships (opens a new tab)See a labeled picture
Semester, term, and academic yearA term is one block of school time. A semester is one kind of term. An academic year is the school’s yearly learning period.
How it works
Many schools have fall and spring semesters; others use quarters or different schedules. A price “per semester” is not the same as a price “per year.”
A small example
If tuition is $4,000 each semester and you attend two semesters, that is $8,000 before summer or other costs.
Start here, one step at a time
- Open the school’s academic calendar.
- Write the first day, last day, payment dates, and add/drop dates for your term.
- Compare every cost and award using the same time period.
Try explaining this word yourself
Before looking back, explain “Semester, term, and academic year” in your own words. Which part of the example shows it?
Then compare your explanation with “A term is one block of school time. A semester is one kind of term. An academic year is the school’s yearly learning period.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“How many terms are included in this price?”
Federal Student Aid: understand aid offers (opens a new tab)See a labeled picture
Simple and compound interestSimple interest uses a principal amount over time. Compound interest also applies interest to accumulated interest when the terms provide for it.
How it works
The compounding schedule and payments matter. Savings and different loans can use different methods, so do not use a single formula for every account.
A small example
With annual compounding and no activity, $100 at 5% becomes $105 after year one, then $110.25 after year two.
Start here, one step at a time
- Ask whether interest uses the original balance, a changing balance, or accumulated interest.
- Use the rate and time period from the agreement; include payments when estimating a loan.
Try explaining this word yourself
Before looking back, explain “Simple and compound interest” in your own words. Which part of the example shows it?
Then compare your explanation with “Simple interest uses a principal amount over time. Compound interest also applies interest to accumulated interest when the terms provide for it.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What balance is used, and how often is interest added?”
Social Security number and cardA Social Security number identifies your Social Security record. The card shows that number and your name.
How it works
It is not a photo ID. A replacement card is free through the Social Security Administration. You often need the number, not the physical card; ask what the process actually requires.
A small example
A replacement card normally keeps the same number. Do not enter that number in this website’s notes.
Start here, one step at a time
- Start at SSA.gov using the official replacement-card process.
- Answer the eligibility questions to learn whether you can finish online or must visit.
- Follow its evidence rules; keep the card secure instead of carrying it every day.
Try explaining this word yourself
Before looking back, explain “Social Security number and card” in your own words. Which part of the example shows it?
Then compare your explanation with “A Social Security number identifies your Social Security record. The card shows that number and your name.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Do you need the number, the physical card, or another accepted document?”
USAGov: get or replace a Social Security card (opens a new tab)See a labeled picture
Student Aid Index — SAIA number used in the federal aid process to help describe financial need.
How it works
It is calculated from FAFSA information. It is not a bill, a scholarship amount, or a promise of how much your family must pay. Your school uses aid rules and its costs to make an offer.
A small example
An SAI of 0 does not mean college costs $0. You still need the school’s actual cost and aid offer.
Start here, one step at a time
- Find the SAI in your FAFSA Submission Summary.
- Check the submitted information for mistakes.
- Compare the school’s aid offer with its full cost.
Try explaining this word yourself
Before looking back, explain “Student Aid Index — SAI” in your own words. Which part of the example shows it?
Then compare your explanation with “A number used in the federal aid process to help describe financial need.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“How did you use my SAI to calculate this offer?”
Federal Student Aid: understand your FAFSA summary (opens a new tab)See a labeled picture
Student loanBorrowed money for education that must be repaid under its terms.
How it works
Compare federal and private terms, interest, fees, when repayment starts, and available protections. Read before accepting; take only what you decide you need.
A small example
Borrowing $5,000 fills a funding gap today but creates a balance you must repay, potentially with interest.
Start here, one step at a time
- Read the loan’s type, amount, rate, fees, and repayment start date.
- Accept only the amount you decide you need and keep track of the total borrowed across school years.
Try explaining this word yourself
Before looking back, explain “Student loan” in your own words. Which part of the example shows it?
Then compare your explanation with “Borrowed money for education that must be repaid under its terms.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What is the total borrowed so far, and what might repayment look like after school?”
Federal Student Aid: understand aid offers (opens a new tab)Subsidized and unsubsidized student loansBoth are loans. The difference includes who pays interest during certain periods.
How it works
For eligible Direct Subsidized Loans, the government pays interest during specified periods. With Direct Unsubsidized Loans, you are responsible for interest in all periods, even when no payment is due. Eligibility and terms differ.
A small example
“No payment due while in school” does not always mean “no interest is being added.”
Start here, one step at a time
- Find the full loan name in your aid offer.
- Read the current federal explanation and your loan agreement.
- Ask the aid office to show an example of the balance when you leave school.
Try explaining this word yourself
Before looking back, explain “Subsidized and unsubsidized student loans” in your own words. Which part of the example shows it?
Then compare your explanation with “Both are loans. The difference includes who pays interest during certain periods.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“When does interest start on this exact loan, and when must payments start?”
Federal Student Aid: subsidized and unsubsidized loans (opens a new tab)See a labeled picture
Test required, optional, or blindDifferent rules about using admission test scores.
How it works
Required means follow the score requirement. Optional generally lets you choose whether to submit. Blind or free generally means scores are not considered for admission. Other uses, such as scholarships or placement, can have different rules.
A small example
A school can be test optional for admission while a particular scholarship asks for a score.
Start here, one step at a time
- Open the admissions page for your entry year.
- Check separate scholarship and program rules; call admissions if the wording is unclear.
Try explaining this word yourself
Before looking back, explain “Test required, optional, or blind” in your own words. Which part of the example shows it?
Then compare your explanation with “Different rules about using admission test scores.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“What are the separate score policies for admission, this major, scholarships, and placement?”
College Board: SAT in a test-optional world (PDF) (opens a new tab)TranscriptAn official record of courses and grades from a school.
How it works
Request it through the school’s registrar, counseling office, or approved portal. A screenshot may not meet an official-transcript requirement.
A small example
A college may require your high school to send the final transcript after graduation.
Start here, one step at a time
- Contact your school’s counselor or registrar.
- Give the exact recipient and deadline; check that the official record arrived.
Try explaining this word yourself
Before looking back, explain “Transcript” in your own words. Which part of the example shows it?
Then compare your explanation with “An official record of courses and grades from a school.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Who must send it, where should it go, and what is the deadline?”
Tuition and feesTuition is the charge for instruction; fees are separate charges for specified services or activities.
How it works
Find out whether tuition is per credit, per term, or a flat amount. Books, housing, food, and transportation may be extra.
A small example
At an invented $200 per credit, 12 credits cost $2,400 in tuition before fees and living costs.
Start here, one step at a time
- Find the school’s tuition page for your residency and program.
- Confirm whether the number is per credit, semester, or year and add required fees.
Try explaining this word yourself
Before looking back, explain “Tuition and fees” in your own words. Which part of the example shows it?
Then compare your explanation with “Tuition is the charge for instruction; fees are separate charges for specified services or activities.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Is this price per semester or per year, and which required fees are missing?”
Federal Student Aid: understand aid offers (opens a new tab)Variable / floating interest rateAn interest rate that can move up or down under the agreement’s rules.
How it works
A common rule is an index plus a margin. The index is a published starting rate. The margin is the added amount named in the agreement. Your loan or card may use different rules.
A small example
An invented 5% index + 12 percentage-point margin = 17%. If the index becomes 6% and the margin stays 12 points, the result is 18%.
Start here, one step at a time
- Find the rate-change section in the agreement.
- Write down the index, margin, and adjustment timing.
- Ask how a higher rate would affect the payment or payoff time.
Try explaining this word yourself
Before looking back, explain “Variable / floating interest rate” in your own words. Which part of the example shows it?
Then compare your explanation with “An interest rate that can move up or down under the agreement’s rules.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“Which index is used, when does my rate change, and are there limits?”
CFPB: fixed and variable APR (opens a new tab)See a labeled picture
Work-studyA form of aid that can provide part-time work opportunities for eligible students.
How it works
You generally need to obtain a job and earn wages. Do not treat an award amount as money already deposited for tuition.
A small example
A $2,000 work-study offer is not a $2,000 discount on the first bill.
Start here, one step at a time
- Ask financial aid whether the offer requires finding a campus job.
- Apply through the official student employment office and plan around wages paid after work.
Try explaining this word yourself
Before looking back, explain “Work-study” in your own words. Which part of the example shows it?
Then compare your explanation with “A form of aid that can provide part-time work opportunities for eligible students.” and the example above. If it is still unclear, use the question below with the relevant office or provider.
A question you can ask
“How do I apply for jobs, when would I be paid, and are positions available?”
Federal Student Aid: understand aid offers (opens a new tab)What this means for you
School choices affect your learning, time, career options, and possible debt. Admission test scores matter differently at different schools.
What can make it harder
A lower score may weaken a score-based application or miss a particular scholarship threshold. Missing deadlines can remove options regardless of score.
What can help
A stronger score may support admission or meet an award requirement where scores are used. It does not guarantee either. Grades, fit, costs, and other requirements still count.
One next stepRead the lower/higher score lesson below. Check your exact school, major, entry year, and scholarship policies before deciding whether to test or retest.
Read how lower and higher scores affect your options ↓Separate the school’s price from how you pay it
Use one academic year for every number. A school bill alone may leave out books, food, transportation, and housing.
Add the estimated full cost
$12,000 tuition and fees + $10,000 housing and food + $2,000 other costs = $24,000.
Subtract aid you do not need to repay
$24,000 − $9,000 grants and scholarships = $15,000 net price, assuming you meet the award conditions.
Identify money already available
$15,000 − $4,000 savings and committed help = $11,000 still to fund. Do not count uncertain gifts or future earnings as cash already available.
See what a loan actually changes
A $5,000 loan would leave $6,000 still to fund now. The net price remains $15,000; you also take on $5,000 of debt, plus any applicable borrowing costs.
Match due dates to cash
If bills are due before your job pays you, an annual budget can still have a timing gap. Ask the aid office for an itemized offer and the billing office for dates.
What the answer tells youA loan is a way of paying, not a discount. Compare net price, debt, renewal conditions, and payment timing across schools.
Reaching the right campus office
Admissions, billing, financial aid, and housing solve different problems.
What can make it harder
Sending a document to one office may not satisfy another office’s requirement.
What can help
Record the office, requested item, deadline, and confirmation separately.
One next stepCheck receipt of one important submission with the office that needs it.
Fit study time around commitments
An invented 40-hour block remains after sleep and essential personal time.
- 1
Add fixed commitments
12 class hours + 10 work hours + 4 travel hours = 26 hours.
- 2
Find time left
40 − 26 = 14 hours available in this planning block.
- 3
Test a study plan
If planned study requires 18 hours, 18 − 14 = 4 hours do not fit.
What the answer tells youRework commitments with your adviser rather than pretending the missing hours exist.
Go a little deeper
Open a lesson when you need the full explanation. You can return to it at any time.
SAT and ACT: from “what is it?” to test dayYou do not have to figure out registration, studying, and college requirements all at once. Work through one decision at a time.
1. Find out whether you need a test
List two or three colleges or training programs you might attend. Open each official admissions website and look for first-year admission requirements for the year you would start. Separately check scholarships and your intended major. Record “required,” “optional,” or “not considered,” plus the deadline.
Ask your school counselor: “Does our school offer the SAT or ACT during the school day? How do I join that test? Would I need a separate weekend test?” Someone already in college should check transfer requirements; first-year testing rules may not apply.
2. Learn what each test asks you to do
The SAT covers Reading and Writing, and Math. It is digital and uses College Board’s Bluebook app. Each section has two modules; performance on the first influences the difficulty mix in the second. Use official practice so the format feels familiar.
The enhanced ACT tests English, math, and reading for its composite score. Confirm the science and writing options for your exact registration. In school-day programs, the school or contract may decide whether science is included. Read your intended college’s requirements before selecting options.
3. Choose a realistic date and check help before paying
Start at the official College Board SAT registration page or ACT registration page linked below. Compare test dates with the college’s score deadline; the registration deadline comes before test day. Allow for score release and delivery. Record the location, transport plan, current fee, and registration deadline.
Ask your counselor about fee waivers and testing accommodations early. Accommodations are changes such as approved extra time or accessible materials. Follow the test provider’s approval process; a school accommodation plan does not automatically complete that process.
4. Register and keep the confirmation
For a weekend SAT, use your own College Board account; for an ACT, follow the official MyACT registration path. Use the name and information required by the provider. Select the date and test center, follow photo and identification requirements, review the total, and save confirmation.
School-day registration can work differently, so follow your school’s directions.
Keep a calendar entry with the test address, arrival instructions, and any setup deadline. Do not assume selecting a date means registration succeeded—look for the confirmation in your account.
5. Practice in small pieces
Take an official practice test or practice section. Mark questions you missed and write why: unfamiliar idea, misunderstood wording, or ran out of time. Pick one skill to practice with a teacher or the provider’s free resources. Try a few questions, review the explanation, and try again.
A manageable example is three 20-minute sessions in a week: one to learn a skill, one to practice it, and one to review mistakes. Adjust the pace to your schedule. Practice helps you prepare; it cannot promise a particular score.
6. Prepare the device, documents, and trip
For the SAT, check the approved-device list, install or update Bluebook, and complete the required setup before test day. If you need a loaned device, use College Board’s lending process by its deadline. Do not wait until arrival to find out whether a device is available.
For either test, open the current test-day checklist for your exact format. Check acceptable ID, admission information, calculator rules, allowed supplies, arrival time, and prohibited items. Charge required devices and arrange transportation. On test day, follow staff instructions and ask immediately if something is unclear.
7. Read the result and decide the next action
Open your score report when released. Look at section feedback with a counselor, then check each school’s score-submission instructions. Some accept self-reported scores first; others require official delivery. Confirm receipt in the college application portal.
A retest is an option if it fits your deadlines, budget, and practice plan. Ask whether the institution accepts a superscore, which combines specified best section results across tests. Schools decide their own score-use policies. You do not automatically need to take both tests or keep retesting.
Build a registration record you can use
Start with the test provider’s current registration page, then compare the dates against your school, work, transport, and application calendar. Write the test name, date, location, arrival instructions, registration deadline, and the identification instructions that apply to you. Keep the confirmation in a secure folder you can open again.
A practice test and an official admission test are different events; label them clearly.
Before paying, ask the school whether the test is required, optional, or considered for a particular program or scholarship in your entry year. If accommodations or fee assistance may apply, check the official request process early. Do not assume that an accommodation used at school automatically transfers to the testing provider.
Practice the sequence, not just the questions
Take a sample under the provider’s stated conditions, review errors by skill, and choose one skill to practice next. A wrong answer caused by misunderstanding a question needs a different response from an unfinished section caused by pacing. Record the cause and the correction in a study note.
The day before the test, check the official instructions again and prepare the permitted materials and transport plan. If your confirmation is missing or a name is wrong, contact the provider through its official support route. Do not wait until the entry line to resolve a document or registration problem.
Check your understanding
- Explain the main idea of “SAT and ACT: from “what is it?” to test day” without looking back.
- Choose one example above and identify its assumptions or requirements.
- Write the next question you would ask about your own situation.
Official sources & next places to go
College Board: SAT registration (opens a new tab)College Board: how the SAT is structured (opens a new tab)College Board: prepare your Bluebook device (opens a new tab)ACT: official registration (opens a new tab)ACT: test-day instructions (opens a new tab)ACT: enhanced-test questions and answers (opens a new tab)ACT: understand your scores (opens a new tab)What a lower or higher test score can mean for youA test score is one piece of information about one test performance. It is not a measure of your worth, and there is no single “good score” for every school.
How to read the numbers
The SAT total ranges from 400 to 1600, combining Reading and Writing and Math, each from 200 to 800. An example 540 plus 580 gives a total of 1120. That is not “70% correct”; scaled scores are not raw percentages.
ACT section scores range from 1 to 36. For the enhanced test, the composite averages English, math, and reading, rounded according to ACT’s rules. Example: (21 + 24 + 27) ÷ 3 = 24. Science and writing do not raise that three-subject composite.
If the score is lower than a school usually sees
At a school that considers tests, a lower submitted score may make that part of your application less competitive. A published middle score range describes a group of students; it is not automatically a minimum or a prediction for you. Grades, courses, and the school’s other requirements still matter.
A score below a stated scholarship cutoff may make you ineligible for that particular award, while other aid may use different criteria. Check the exact award rather than assuming all scholarships are lost. Placement rules can also differ from admission rules.
If the score is stronger
A stronger score can support an application where scores are considered and may meet a score-based scholarship or placement requirement. It does not guarantee admission, funding, or success in a course. A score alone also does not tell you which school you can afford.
For a hypothetical scholarship requiring a 1200 SAT, a 1210 would meet that score condition and an 1180 would not. Other conditions could still apply. This is an invented example—not an actual scholarship or a universal cutoff.
What you can do next
Make one line per school: current test policy, application deadline, any scholarship score rule, and the published score information. Ask admissions: “How would you use my score? May I apply without it? Is the scholarship rule different?” Follow required reporting rules; do not hide a score where disclosure is required.
If a retest makes sense, use section feedback to choose a few skills to practice first. Also explore programs that fit your current record, community-college or transfer routes, and awards with different requirements. Check each pathway’s entry and transfer rules. Do not let one result stop you from asking about options.
Compare the policies behind two choices
Make a small table with the college or program, the entry year, the published testing policy, and each relevant deadline. Add a separate row for a scholarship if its rules differ from admission. This avoids assuming that “test optional” describes every decision the institution makes.
Suppose one program does not require a score and another scholarship considers it. Your next action is to verify both policies and ask how scores are used, not to label yourself qualified or disqualified based on an unofficial score chart. Keep a copy of the answer and its date.
Choose a response that fits your circumstances
After receiving a score, review preparation time, retesting cost, deadlines, and other application work before choosing another attempt. A higher score may help in one process, but repeatedly testing can consume time needed for coursework or an application essay. Ask an adviser to help compare those tradeoffs.
If you submit a score, verify that the receiving institution has matched it to your application. If you do not submit where that is permitted, check whether you must actively choose that option in the application. A decision on a form and a score sitting in a testing account are different things.
Check your understanding
- Explain the main idea of “What a lower or higher test score can mean for you” without looking back.
- Choose one example above and identify its assumptions or requirements.
- Write the next question you would ask about your own situation.
Prove where you live: DMV, Post Office, and no bills in your nameA bill accepted in one place may be refused somewhere else. Start with the exact service.
1. Name the job before gathering papers
Say what you are doing: “I am applying for my first state ID,” “I want a REAL ID,” “I need a PO Box,” or “I am forwarding mail.” These are different services with different lists. Identity means who you are. Residency means where you live. A passport may prove identity without proving your current street address.
2. For a license or state ID, use your state’s list
Open the official state motor-vehicle site using the directory below. Choose the exact service and your age. Look for “documents,” “residency,” or “proof of address.” Common categories on some state lists include utility bills, leases, bank statements, and government mail. No category is accepted everywhere.
California REAL ID is one example: its checklist calls for two different residency documents and lists several categories, including certain bills and financial records. California’s rule is an example, not a rule for every state. Read the current list for names, dates, address, and printed-document requirements.
A standard ID application may have different rules.
3. At the Post Office, use the postal service’s list
For a PO Box, USPS Form 1093 calls for two acceptable current IDs: one photo identification and one qualifying non-photo address document. The non-photo examples on that form include a lease, mortgage or deed of trust, voter or vehicle registration, and home or vehicle insurance.
Utility bills are not on that PO Box form’s accepted-ID list. A Social Security card, birth certificate, or credit card is not a substitute for the listed postal IDs. For a different service, such as collecting mail or identity verification, check USPS’s service-specific rules instead of reusing the DMV list.
4. If you are moving, forwarding is only one step
Start on USPS.com, choose the real change-of-address service, and follow its identity-verification instructions. If directed to visit a Post Office, bring the barcode or instructions and the exact IDs requested. An extra address document may be needed when your primary ID does not show the required address.
Forwarding eligible mail does not update your driver’s license, bank, school, voter record, or insurance automatically. Update those organizations separately through their own official processes.
5. If no bills show your name, ask about the approved alternative
Do not put your name on someone else’s bill yourself. Ask: “I live with my parent/relative/roommate and have no bills in my name. What is your approved residency process?” A state or organization may allow a relationship record, signed residency form, school/housing letter, or other evidence. Some offer a separate route for people without fixed housing.
Acceptance is specific to that service.
Before leaving home, check: correct name, physical address, required date range, enough different documents, and the right format. Ask whether a downloaded statement must be printed, whether originals are needed, and how any name difference is handled. Save the official list with your appointment details.
Prepare for the exact office
Write the name of the receiving office and the specific transaction, such as renewing an ID or opening a PO Box. Read that office’s current list and note acceptable document types, required dates, whose name must appear, and whether a physical address is required. A mailing address and a residence address may serve different purposes.
If a bill is in someone else’s name, explain that situation before the visit and ask which alternatives the office accepts. Do not alter a bill or assume a handwritten note qualifies. Keep the official answer with the appointment information.
Check the whole packet before leaving
Compare your documents against the list one by one. Make sure names, dates, and addresses are readable and that the required originals or copies are available. If you plan to use a digital statement, confirm whether the office needs a printed version.
If a document is rejected, ask which requirement it failed and what would satisfy it. Record that explanation rather than ordering several replacements at random. This turns a frustrating return visit into a specific correction and helps avoid paying for an unnecessary certified copy.
Check your understanding
- Explain the main idea of “Prove where you live: DMV, Post Office, and no bills in your name” without looking back.
- Choose one example above and identify its assumptions or requirements.
- Write the next question you would ask about your own situation.
Official sources & next places to go
USAGov: state motor-vehicle services (opens a new tab)California DMV: example of a state document checklist (opens a new tab)USPS: PO Box application and ID list (PDF) (opens a new tab)USPS: ID accepted for each postal service (opens a new tab)USPS: mail forwarding and identity checks (opens a new tab)USPS: find a Post Office and its services (opens a new tab)Get or replace a passport, birth certificate, or Social Security cardGo to the office that issues the record. Each replacement follows its own steps.
1. Start with what is missing
Write the document name and why you need it. Ask the place requesting it whether it needs a certified copy, original, or another accepted form. Do not order every possible record. Use official government routes instead of paying an unnecessary middleman.
2. Birth certificate
For a U.S. birth, use the vital-records office for the state or territory where you were born. It explains who can order, identity evidence, fees, and delivery. The government keeps the birth record; it issues certified copies from that record. A hospital’s decorative keepsake is different.
If you do not have the usual photo ID, call the records office for its alternative evidence process. For a birth abroad, the process depends on the record: a Consular Report of Birth Abroad and a foreign birth certificate have different issuing authorities. If a copy is lost, request a replacement certified copy.
If it was stolen, ask the issuing office about any relevant reporting steps and use IdentityTheft.gov if you suspect misuse.
3. Social Security card
Go to SSA.gov and choose “Replace card.” Replacement is free. Its questions tell you whether your request can finish online or needs an office visit. Follow the current evidence instructions; do not assume photocopies or notarized copies satisfy SSA. You may not need a physical replacement if knowing your number is enough for the service you need.
A replacement does not normally give you a new number. If you suspect identity theft, follow IdentityTheft.gov’s recovery steps and consider the official credit-freeze guidance. Keep your card secure rather than carrying it for everyday shopping.
4. First passport or replacement application
On Travel.State.gov, choose your age and application situation. First-time adult applicants commonly use the in-person DS-11 route. Follow that route’s list for citizenship evidence, photo identification, required copies, a compliant photo, and separate fees. Do not sign until the instructions tell you to.
Children under 16 and ages 16–17 have additional rules about attendance and parent/guardian involvement.
As reviewed September 17, 2026, the State Department lists routine processing at 4–6 weeks and expedited processing at 2–3 weeks. Mailing time is additional; allow for time in both directions. These are published estimates, not delivery promises. Recheck the linked processing page and urgent-travel instructions before booking.
5. Lost or stolen valid passport
Use the State Department’s official reporting process promptly. Once reported lost or stolen, the passport cannot be used for international travel even if found later. Reporting and replacing are separate tasks; follow the site’s DS-11 replacement instructions and any reporting form it requests.
Abroad, contact the nearest U.S. embassy or consulate for the applicable help.
Keep application or report confirmations securely. Do not put scans, Social Security numbers, or passport numbers in Life’s Checklists notes.
Work backward from the missing record
Start with the issuing agency and the exact record you need. List what evidence you already have and what the official application requires. If one missing document is needed to obtain another, ask the agency which alternative evidence or sequence applies to your situation. Do not assume every replacement starts with the same identity papers.
Keep a simple tracker with the agency, submission date, confirmation, quoted processing range, and next follow-up date. Store sensitive copies separately in protected storage. The tracker should help you find a request without exposing the underlying identity information.
Avoid paying for the wrong service
Check whether a website is the actual issuer or a third-party service charging to forward a request. Read the official fee schedule and what that fee includes before paying. A fee for faster shipping is different from faster processing, and neither automatically guarantees arrival before an appointment.
After receiving a replacement, check the name and relevant details immediately and follow the issuer’s correction process for any error. Update your secure document locator so you know where the original is kept. Do not upload a full identity document into ordinary checklist notes.
Check your understanding
- Explain the main idea of “Get or replace a passport, birth certificate, or Social Security card” without looking back.
- Choose one example above and identify its assumptions or requirements.
- Write the next question you would ask about your own situation.
Official sources & next places to go
USAGov: get a certified birth certificate (opens a new tab)USAGov: get or replace a Social Security card (opens a new tab)Social Security Administration: free replacement card (opens a new tab)Social Security Administration: required evidence (opens a new tab)U.S. State Department: passport applications (opens a new tab)U.S. State Department: current passport times (opens a new tab)U.S. State Department: lost or stolen passports (opens a new tab)FTC: identity-theft recovery steps (opens a new tab)Find grants and scholarships, then read your aid offerStart with free applications and one school’s financial-aid office.
1. Ask the right office
Go to your college’s official website and search “financial aid.” Use the contact number on that page. Say: “I am a new student. Which grants and scholarships can I apply for, and what are the deadlines?” If you are still in high school, your counselor can help you find this office and local awards.
2. Apply for need-based aid
Complete the correct FAFSA year through StudentAid.gov. It is free. Follow the questions about contributors, tax information, assets, consent, and signatures. Each contributor uses their own account. A contributor supplies information; that alone does not make them a borrower.
After processing, read your FAFSA Submission Summary and fix any errors through the official process. Respond to school requests and check separate state grant applications. A processed FAFSA is not the final school aid offer.
If family finances changed or you cannot obtain required family information, ask the aid office about the appropriate process rather than guessing.
3. Apply for scholarships one at a time
Look at the college’s scholarship page, your counselor’s list, legitimate community foundations, employers, and organizations you belong to. Read eligibility before spending time on an application. Gather the requested transcript, short essay, recommendation, or other evidence. Ask recommenders early.
Write the amount, deadline, renewal rules, and official application link in a simple list. Submit through the award provider’s verified process and keep confirmation. No search service can guarantee you an award. Avoid paying someone who promises guaranteed scholarship money.
4. Compare the offer without hiding debt
Separate grants/scholarships, work-study, and loans into three groups. Grants and scholarships are usually not repaid if their conditions are met. Work-study generally means you must find a job and earn wages. Loans must be repaid under their terms.
Ask how an award reaches you, which expenses it covers, when funds arrive, and what happens if you drop a class, leave school, or receive other aid. Some conditions can require repayment of gift aid. A renewal may require another application or a minimum GPA.
Example: $20,000 annual costs − $7,000 grants/scholarships = $13,000 net price. A $4,000 loan helps fund that $13,000 but does not reduce net price. You still have $9,000 to fund now and a loan to repay later.
Build an offer comparison with like-for-like periods
Choose one academic year or term and use it for every school you compare. Put tuition, required fees, housing, food, books, transport, and other relevant costs in separate rows. Then separate grants and scholarships from loans and potential work earnings. Do not subtract a loan as though it were a discount.
Next to every award, write its renewal requirements, deadline, and how it is disbursed. A scholarship paid after the first bill is due can leave a timing gap even when the annual total appears sufficient. Ask billing and financial aid which office handles that gap.
Confirm completion rather than assuming it
After submitting an application or requested document, check the official portal for missing items and receipt status. Keep the confirmation and review messages regularly. A submitted form, a processed form, and an award accepted under its terms can be distinct stages.
If circumstances change, contact the financial-aid office and ask about the appropriate review process. Describe the change accurately and use its secure document method. Avoid guessing numbers or relying on a scholarship promise from an unverified service to fill a funding gap.
Check your understanding
- Explain the main idea of “Find grants and scholarships, then read your aid offer” without looking back.
- Choose one example above and identify its assumptions or requirements.
- Write the next question you would ask about your own situation.
Official sources & next places to go
Federal Student Aid: grants (opens a new tab)Federal Student Aid: find and apply for scholarships (opens a new tab)Federal Student Aid: FAFSA starting steps (opens a new tab)Federal Student Aid: after you submit the FAFSA (opens a new tab)Federal Student Aid: understand your FAFSA summary (opens a new tab)Federal Student Aid: understand aid offers (opens a new tab)Find your campus, parking, classes, and place to livePractice the trip before your first day so every location is not new at once.
1. Find the right campus map
Search the school’s official website for “campus map.” Make sure it is the correct campus—one college may have several. If there is a printable map or PDF, download it from that school. If not, save the building names and official map link; ask the visitor or student-services office for a paper map.
Use your actual class schedule to find each building and room. A building abbreviation is not necessarily its street address. Walk the route before classes if possible and locate accessible entrances, bathrooms, the library, and student services. The illustration here is only an example, not a map of your school.
2. Find the parking office and its number
On the school’s site, search “parking services” or “transportation.” Open the Contact page or official staff directory for the phone number. Ask: “I am a new commuting/resident student at this campus. Which permit do I need, where does it work, and where may I park while buying it?”
Student, resident, visitor, accessible, timed, and reserved areas can have different rules. A permit may cover only specific lots and times and may not guarantee a space. Read posted signs, register the correct vehicle if required, and check event or overnight restrictions. If using transit, practice the route and check the last return trip.
3. Match housing to your household and budget
A dorm or residence hall is usually school-managed housing with room, roommate, meal-plan, and break-period rules. Family housing is housing designed for eligible students with partners or dependents; eligibility and availability vary.
Off-campus means outside school-managed housing and may be a private apartment, house, or room. “Apartment” describes a type of home and can be on or off campus.
Ask about full yearly cost, utilities, deposits, move-in dates, summer/break access, cooking, transport, and who handles repairs. Do not assume a dorm contract ends whenever a student leaves school. Read the cancellation terms. Contact the school housing office before paying an unfamiliar private listing.
4. Turn course credits into a weekly plan
Use the degree plan with an academic adviser. Check prerequisites, which credits count toward your program, and the school’s full-time and aid rules. Make time for class, study, work, travel, food, and rest.
If a course is difficult, use tutoring or office hours early. Before dropping a class, ask both the adviser and financial-aid office about grades, aid, housing, and graduation effects. Do not assume dropping one course affects only that course.
Rehearse one complete day
Choose a real class day and trace the journey from home to the first room, between classes, and back home. Include parking or transit, walking time, meals, accessibility requirements, and any job shift. A schedule that works on paper can fail if two buildings are farther apart than expected.
Identify one help location you can reach in person and one official contact you can use remotely. Save the correct campus map offline if possible. If a room changes, update your route instead of relying on an old screenshot indefinitely.
Make a fallback before it is needed
Write what you would do if the usual bus is missed, a parking lot is full, or a building entrance is inaccessible. Check which offices can help with those specific problems. Do not assume a friend’s permit, building access, or housing permission transfers to you.
At the end of the first week, revise the plan using actual travel and study time. Move unrealistic chores or work blocks before they become repeated conflicts. Ask an adviser about academic changes and the relevant offices about financial or housing effects before dropping or switching a class.
Check your understanding
- Explain the main idea of “Find your campus, parking, classes, and place to live” without looking back.
- Choose one example above and identify its assumptions or requirements.
- Write the next question you would ask about your own situation.
Use a card and understand the first billFirst decide whether you are spending money you have or borrowing money.
1. Identify the card
Debit usually spends money in your bank account. Credit creates a debt to the card issuer. Prepaid usually spends money loaded onto the card. A payment-network logo does not tell you which kind it is. Check the account agreement or ask the issuer.
Choosing “credit” at checkout with a debit card usually changes how the payment is processed; it does not turn the purchase into a credit-card loan or automatically build credit. Pending purchases can reduce available money before they fully post.
2. Read the credit-card statement
Find the statement balance, minimum payment, and due date. The statement balance is a snapshot when the billing period closed. The current balance may include newer purchases. Pay at least the required minimum on time to meet that payment requirement, but paying only that amount can leave interest-bearing debt.
Many cards avoid purchase interest when you have a grace period and pay the full required statement balance on time. Cash advances and other transactions may have different rules. Ask the issuer which transactions qualify and whether you have already lost the grace period.
3. Understand a changing APR
A variable rate can follow an index, such as prime, plus an extra percentage called a margin. Example: 5% index + 12 percentage-point margin = 17% APR. If the index becomes 6% with the same margin, the result is 18%. That is a one-percentage-point increase.
The Federal Reserve influences certain short-term rates. Banks set their own prime rates; your contract determines how an index change affects your account. A fixed-rate loan generally follows its fixed-rate contract. A card described as fixed can still change under applicable rules and notice requirements.
Debit purchases do not normally have a borrowing APR, though account or overdraft fees may apply.
4. Estimate interest carefully
A rough example with a constant $1,000 balance, 24% APR, and 30 days is $1,000 × 0.24 ÷ 365 × 30 ≈ $19.73. Real cards may use daily balances, compounding, fees, and grace-period rules, so this is not a prediction of your bill.
Set reminders, review transactions, and contact the issuer before a missed payment if you are struggling. Never carry debt just because someone says paying interest is necessary to build credit.
Check a payment from request to completion
Find the amount you intend to pay, the due date, and the source account. Read the issuer’s payment timing instructions. After submitting, save the confirmation and later check that the payment posted and the source account has enough money for other obligations. A scheduled payment is not yet the same as a completed payment.
If you use automatic payments, confirm whether the setting pays a minimum, fixed amount, or full statement balance. Review changes after replacing a bank account. Autopay can help with routine work, but it does not replace checking transactions and available funds.
Handle a confusing purchase carefully
Compare the merchant, transaction date, pending or posted status, and amount with your receipt. A temporary hold may differ from the final charge, but an unfamiliar transaction still deserves prompt verification. Contact the issuer through its official channel when needed.
Do not send full card numbers through ordinary chat or put them in checklist notes. Record the date, question, case reference, and promised follow-up securely. Before changing payment behavior because of a confusing bill, ask the issuer to explain the exact balance and interest treatment that applies.
Check your understanding
- Explain the main idea of “Use a card and understand the first bill” without looking back.
- Choose one example above and identify its assumptions or requirements.
- Write the next question you would ask about your own situation.
Official sources & next places to go
CFPB: debit, prepaid, and credit cards (opens a new tab)CFPB: credit-card contract terms (opens a new tab)CFPB: credit-card grace periods (opens a new tab)CFPB: fixed and variable APR (opens a new tab)Federal Reserve: prime rate and the federal funds rate (opens a new tab)Read a loan from the amount borrowed to the last paymentUse a written offer and ask someone to show every number before you agree.
1. Identify the people and the money
The borrower owes the money. The lender supplies it. A servicer may collect payments. A co-signer also accepts legal repayment responsibility. Find the amount borrowed and the amount actually received: a fee can be taken out before money reaches you.
Example: a $2,000 loan with a $100 fee taken from the proceeds may deliver $1,900 while you still owe $2,000 principal. Ask for the exact disclosure and what the fee changes.
2. Find the rate, length, and total
Interest is the charge for using borrowed money. APR is a yearly rate or cost measure; included fees depend on the kind of loan. Loan term is how long the scheduled repayment lasts. A longer term can lower a monthly payment while increasing total interest.
Write the payment amount, number of payments, total repayment, fees, and whether the rate can change. For an example loan requiring 24 payments of $100 with no other payments, the scheduled total is $2,400. Compare that with what you receive, and ask about any separate fees.
3. Ask what happens when the plan changes
Find late-payment charges, prepayment rules, collateral, and default consequences. Collateral is property used to secure the debt; failing to repay can put it at risk under the contract and law. A payment pause is not automatically interest-free. Refinancing replaces debt with a new loan and can change fees or protections.
For student loans, distinguish federal and private terms, subsidized and unsubsidized interest, when repayment starts, and when unpaid interest could be added to principal. Do not assume interest vanishes while you attend school.
4. Make each person’s role explicit
A co-signer is not just a reference and is not released merely because the main borrower says they will handle everything. Ask the lender about any release conditions and obtain written confirmation of a release. An authorized card user is a different role; the primary account holder generally owes that card debt.
Keep your signed agreement and payment schedule securely. If a word is unclear, ask: “Please explain it using a small dollar example.” You do not need to sign before understanding.
Put two offers on one comparison sheet
For each offer, record the amount received, amount financed, rate or APR as disclosed, payment amount, number of payments, fees, and total repayment. Compare the same borrowing amount and repayment period first. If an offer uses a different period, mark it clearly so a smaller payment does not look like a cheaper loan by accident.
Use a simple example to check understanding: twenty payments of $120 total $2,400 before any additional required amounts. Then ask what money actually reaches the borrower and whether any fee has already been deducted. The written disclosure determines the real comparison.
Plan the first payment before signing
Locate the servicer’s verified contact, first due date, payment method, and how to confirm a payment posted. Check what happens to interest and fees during any delay or payment arrangement. A verbal assurance should be reconciled with the actual written terms before you rely on it.
If someone will co-sign, give that person time to read their own obligations and ask questions independently. Keep the signed agreement and payment schedule securely. Do not borrow just because a lender approves an amount; fit the commitment to the household budget and foreseeable changes.
Check your understanding
- Explain the main idea of “Read a loan from the amount borrowed to the last payment” without looking back.
- Choose one example above and identify its assumptions or requirements.
- Write the next question you would ask about your own situation.
Official sources & next places to go
CFPB: read a Loan Estimate (opens a new tab)CFPB: credit-card contract terms (opens a new tab)CFPB: a co-signer’s responsibility (opens a new tab)CFPB: student-loan co-signers (opens a new tab)Federal Student Aid: subsidized and unsubsidized loans (opens a new tab)CFPB: fixed and variable APR (opens a new tab)Useful places to start
- Official FAFSA starting instructions (U.S.) (opens a new tab)
Choose the application year that matches when you plan to attend school.
- Understand and compare aid offers (opens a new tab)
Use this alongside each school’s offer, then ask its aid office about unclear amounts.
Ready for one small action?
Go back to your path. Each stage has instructions, questions to ask, and a checklist.
U.S. starting points · Foundation references reviewed September 17, 2026; expanded content added September 19, 2026. Examples use invented amounts unless stated otherwise. Requirements, rates, and policies vary; use the linked official sources and the terms that apply to you.
Use notes for plans and reminders. Keep passwords, account numbers, and sensitive documents in a secure storage service.